
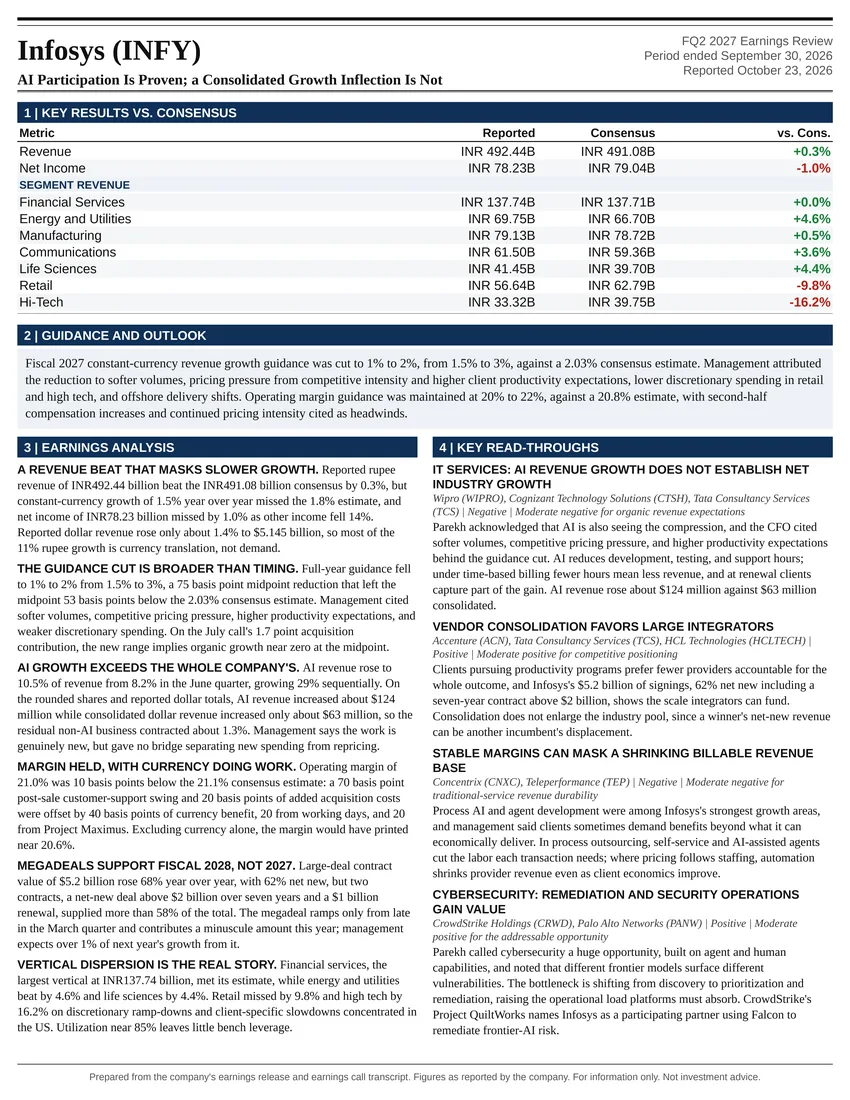
AI Participation Is Proven; a Consolidated Growth Inflection Is Not
Earnings Reports
Earnings Reports
The Atlas Peak Research earnings library: full analysis and read-through documents, one-page exhibits, and PDFs for every covered company, searchable by company, sector, and quarter.
40Reports
40Companies
9Sectors covered
October 23, 2026Most recent report
Looking for a phrase inside the documents? Search the full text.
40 reports
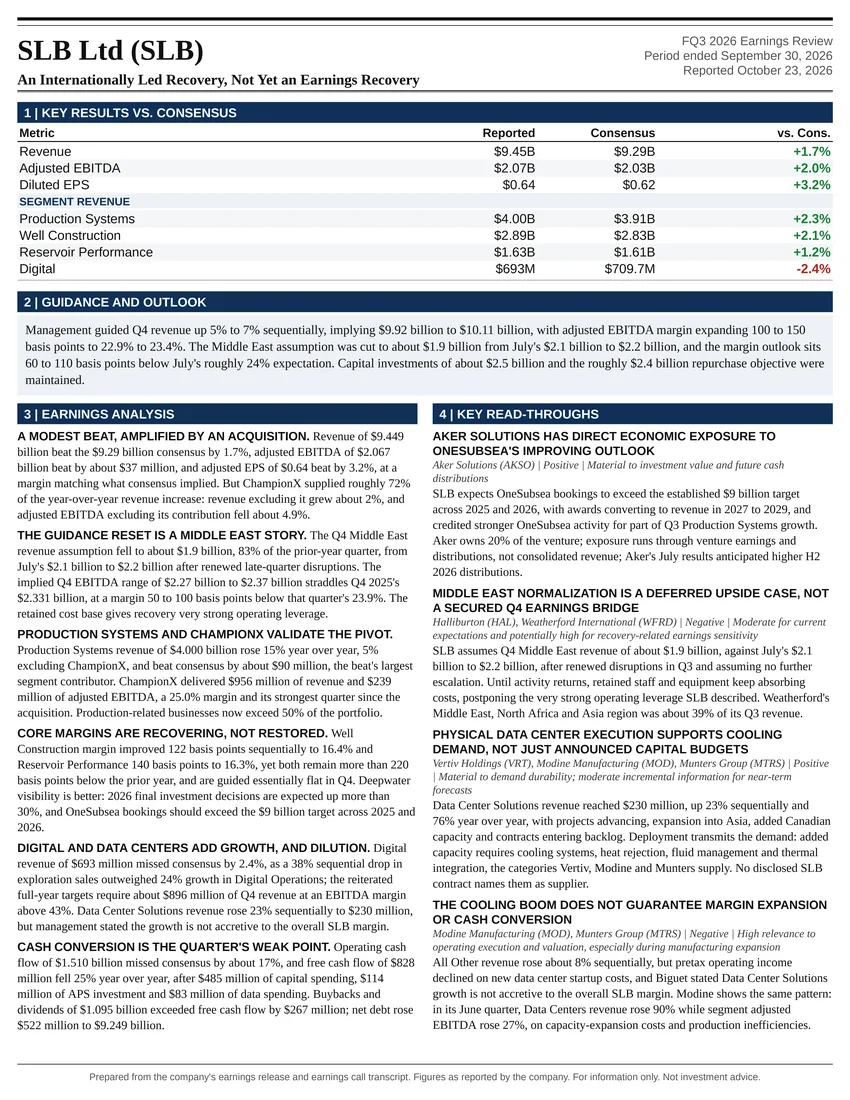
An Internationally Led Recovery, Not Yet an Earnings Recovery
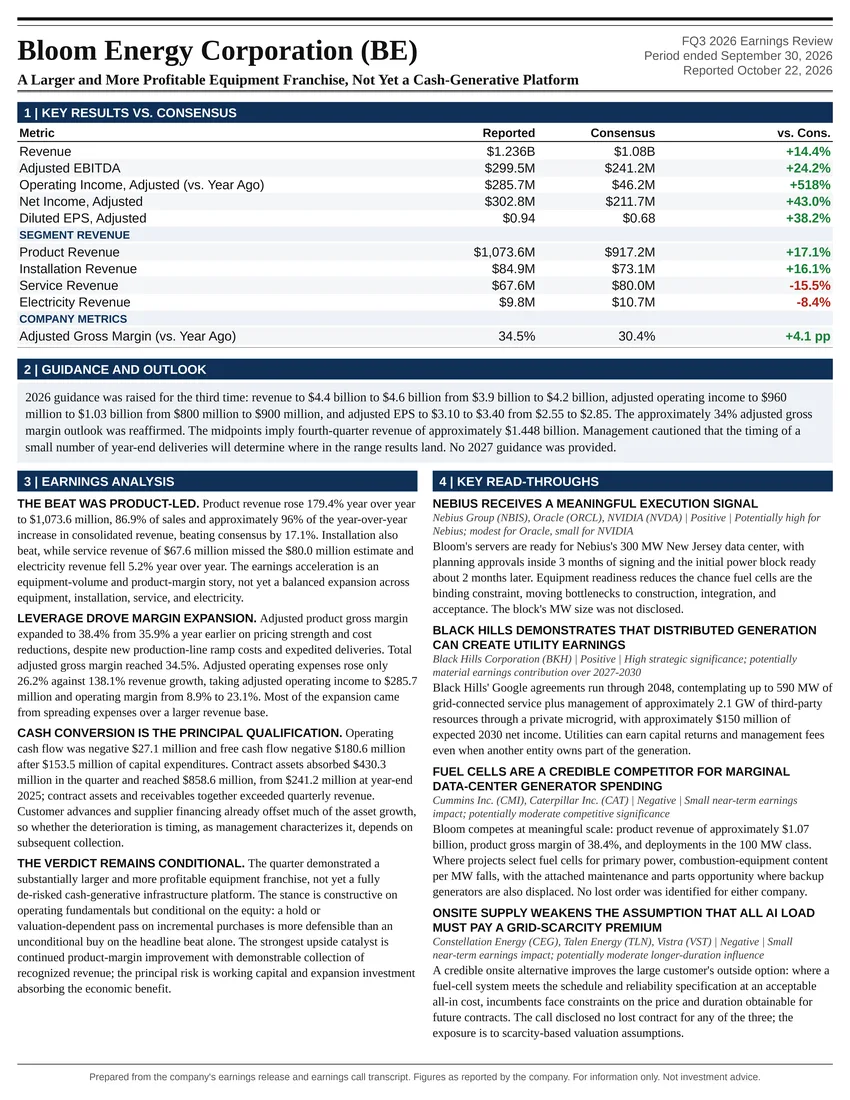
A Larger and More Profitable Equipment Franchise, Not Yet a Cash-Generative Platform
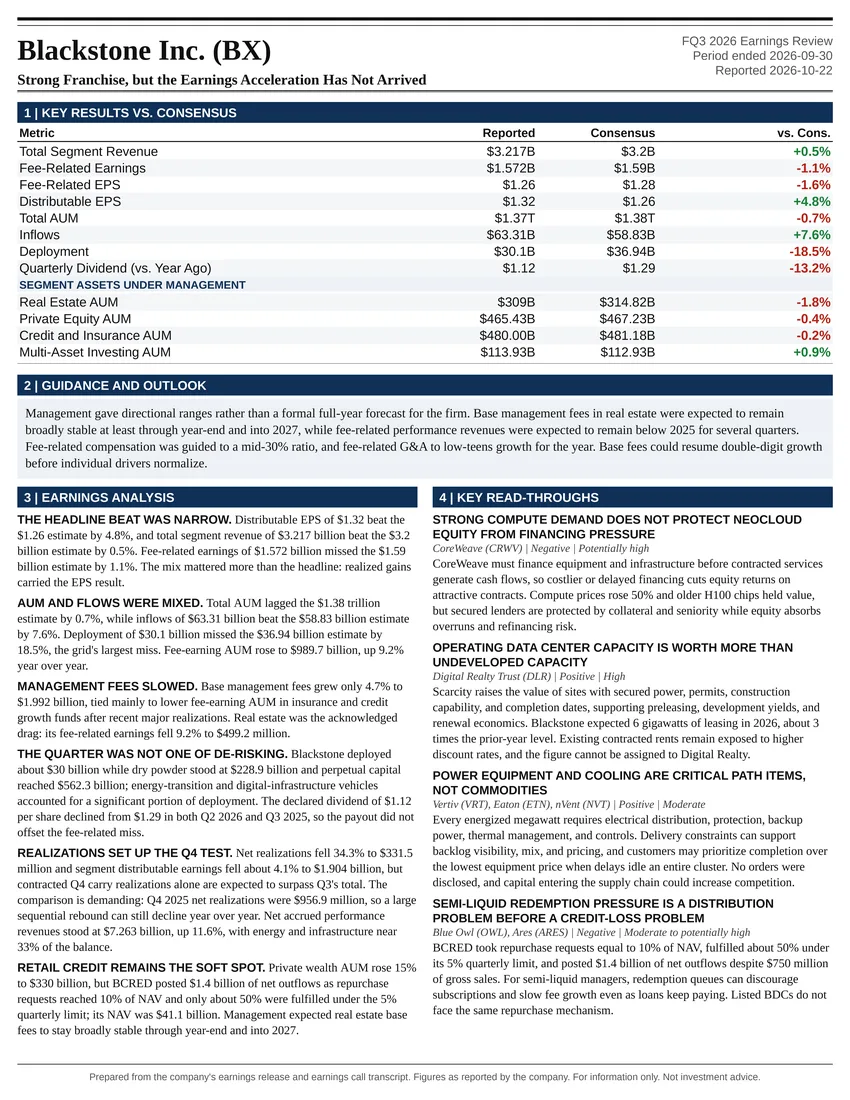
Strong Franchise, but the Earnings Acceleration Has Not Arrived
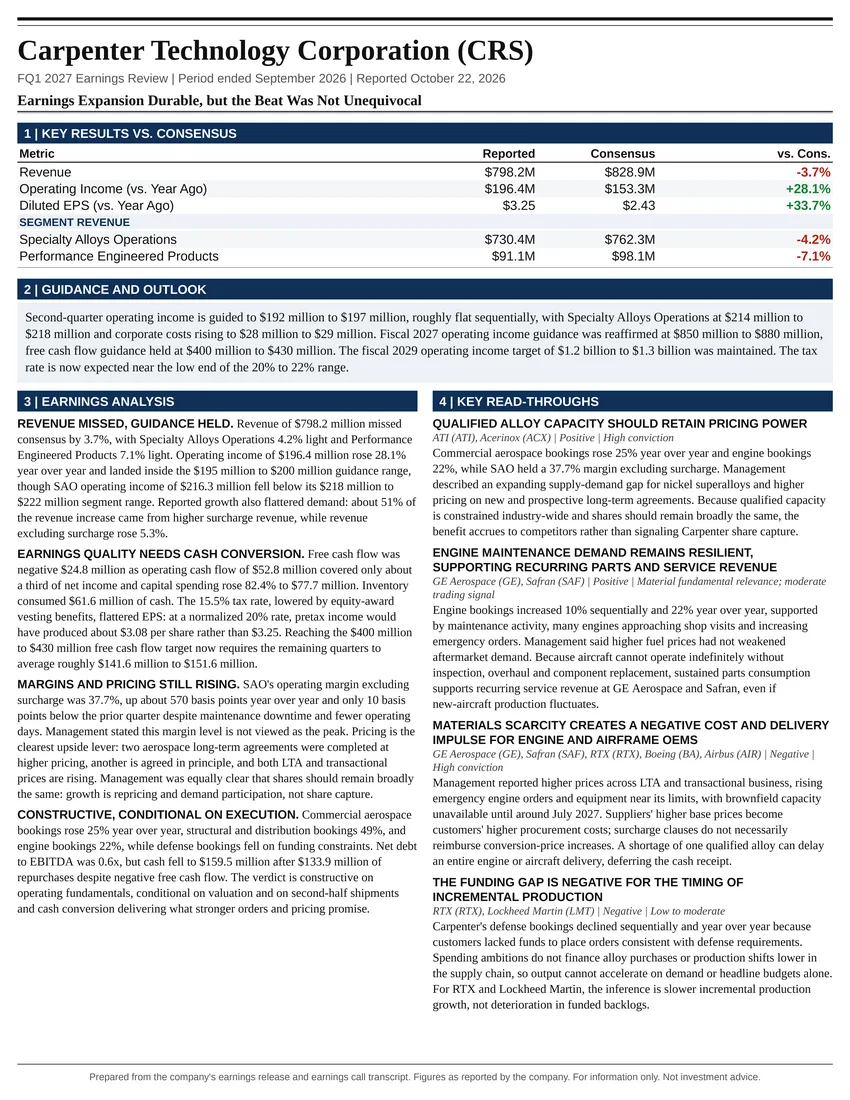
Earnings Expansion Durable, but the Beat Was Not Unequivocal
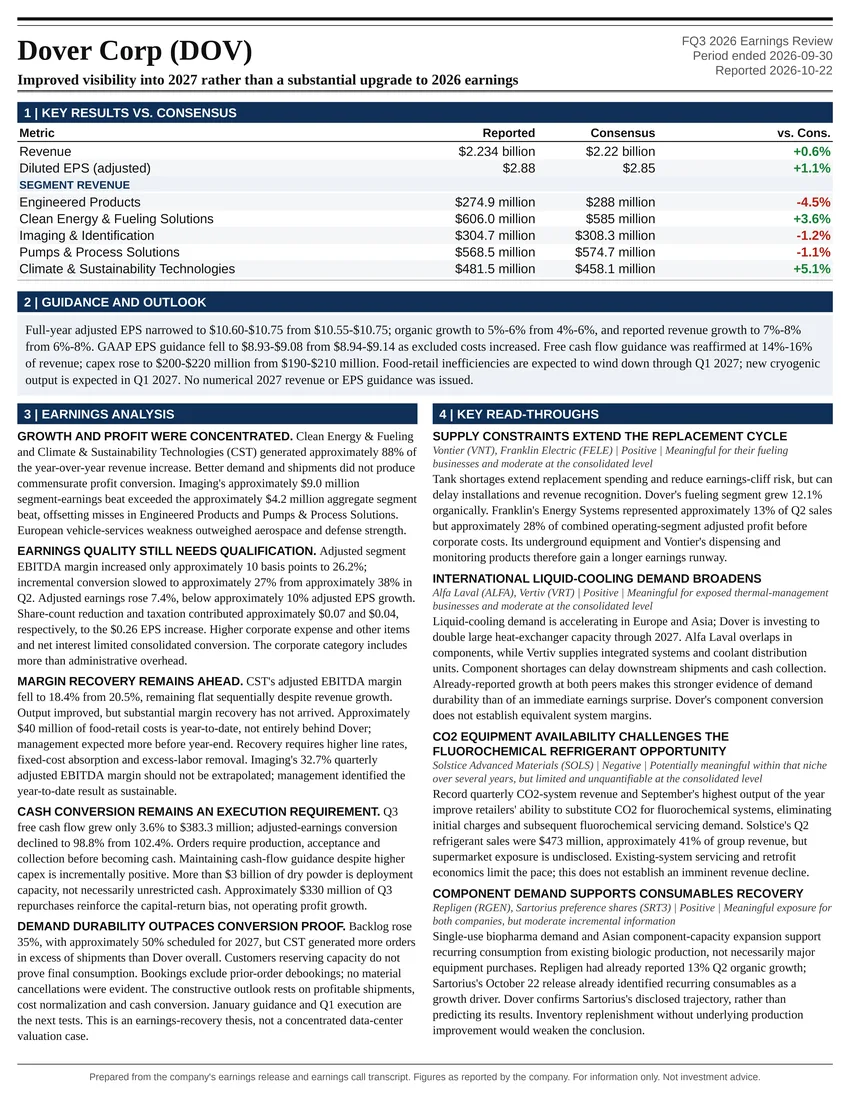
Improved visibility into 2027 rather than a substantial upgrade to 2026 earnings
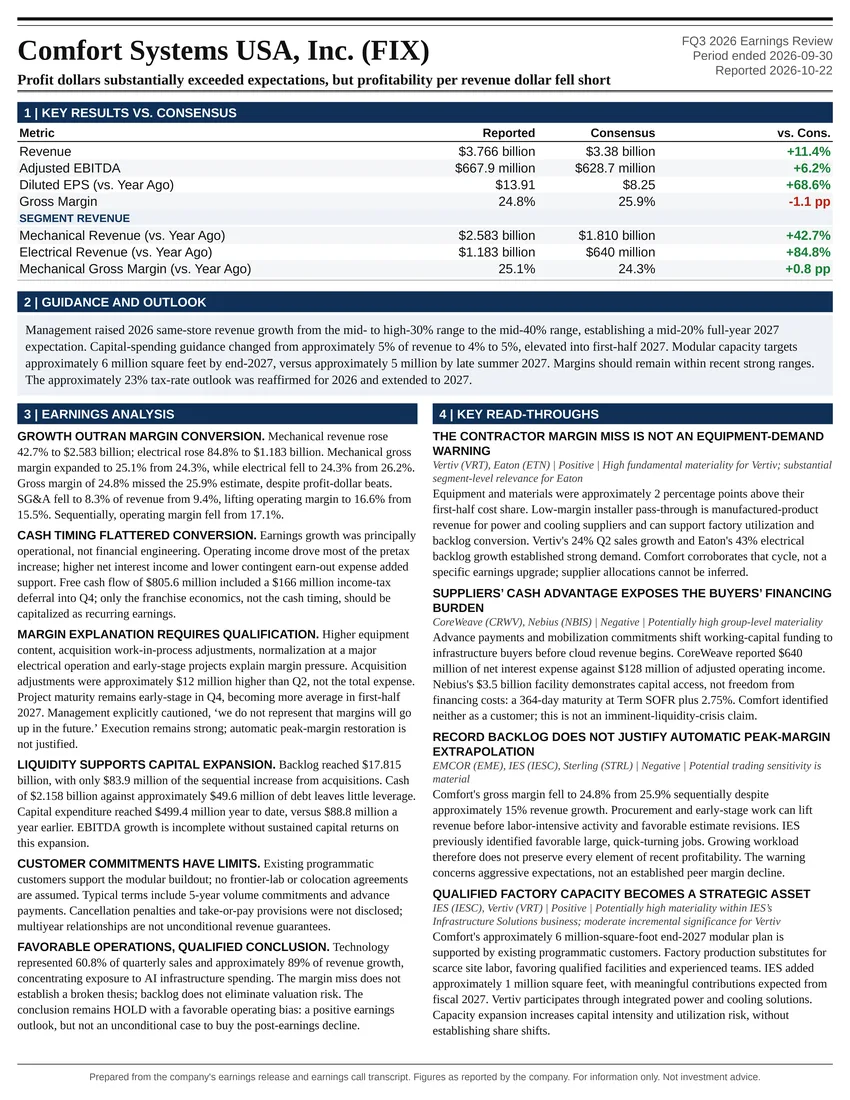
Profit dollars substantially exceeded expectations, but profitability per revenue dollar fell short
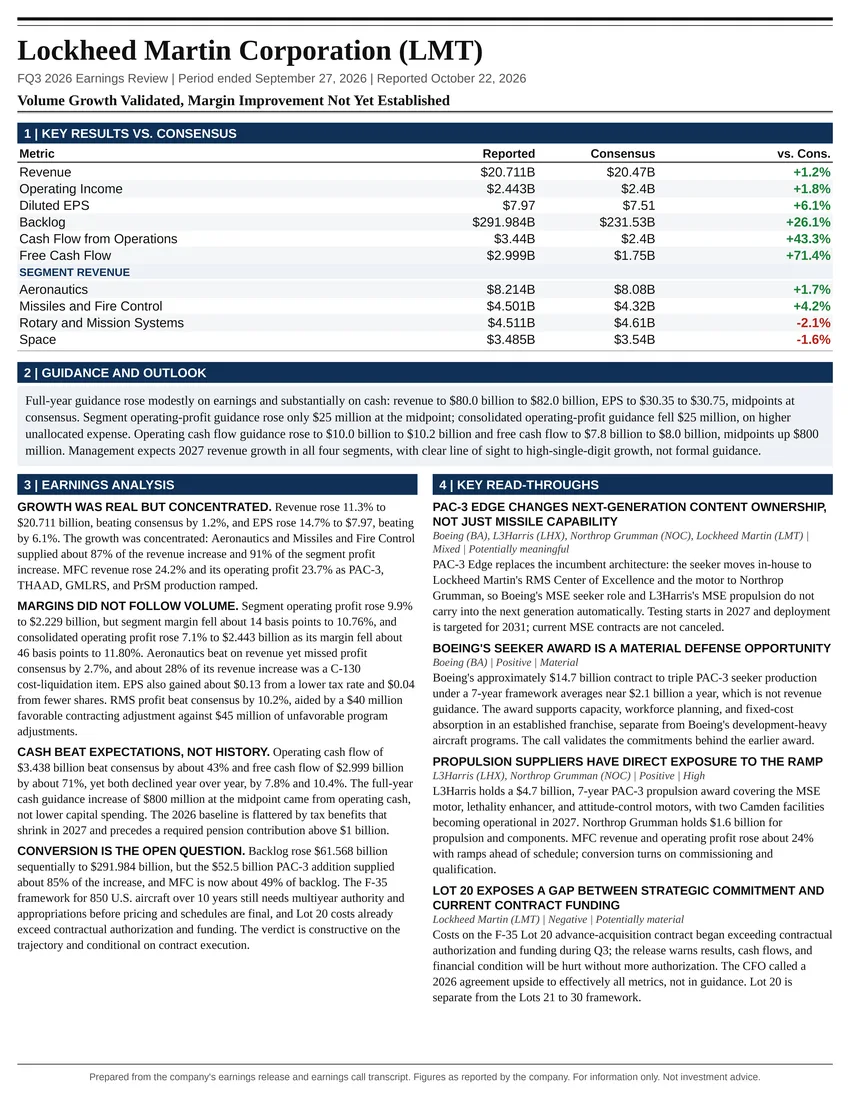
Volume Growth Validated, Margin Improvement Not Yet Established
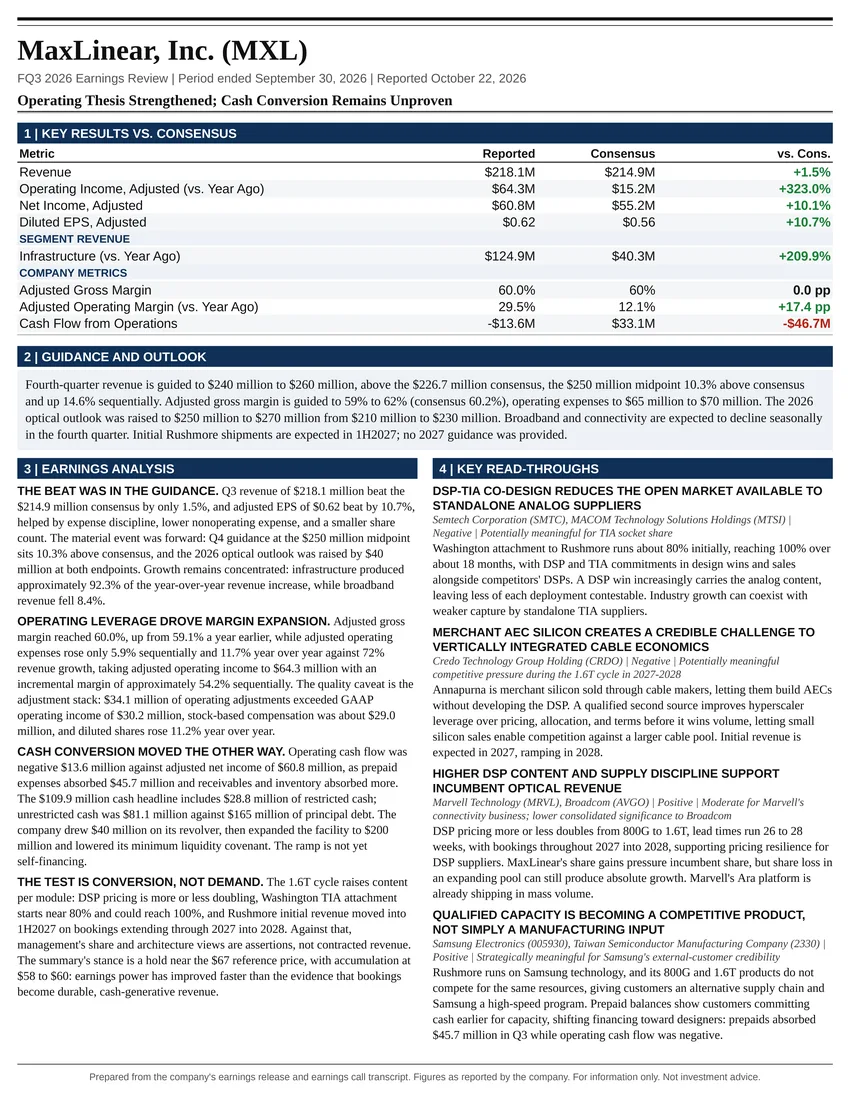
Operating Thesis Strengthened; Cash Conversion Remains Unproven
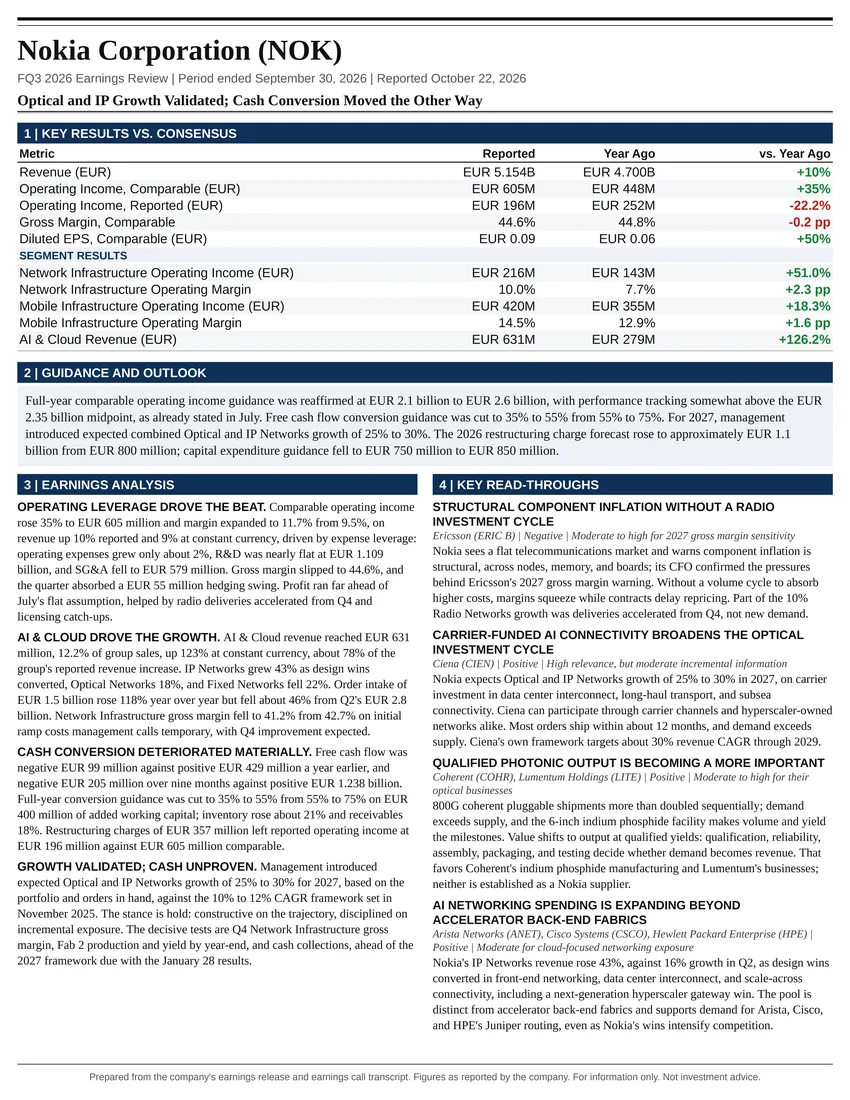
Optical and IP Growth Validated; Cash Conversion Moved the Other Way
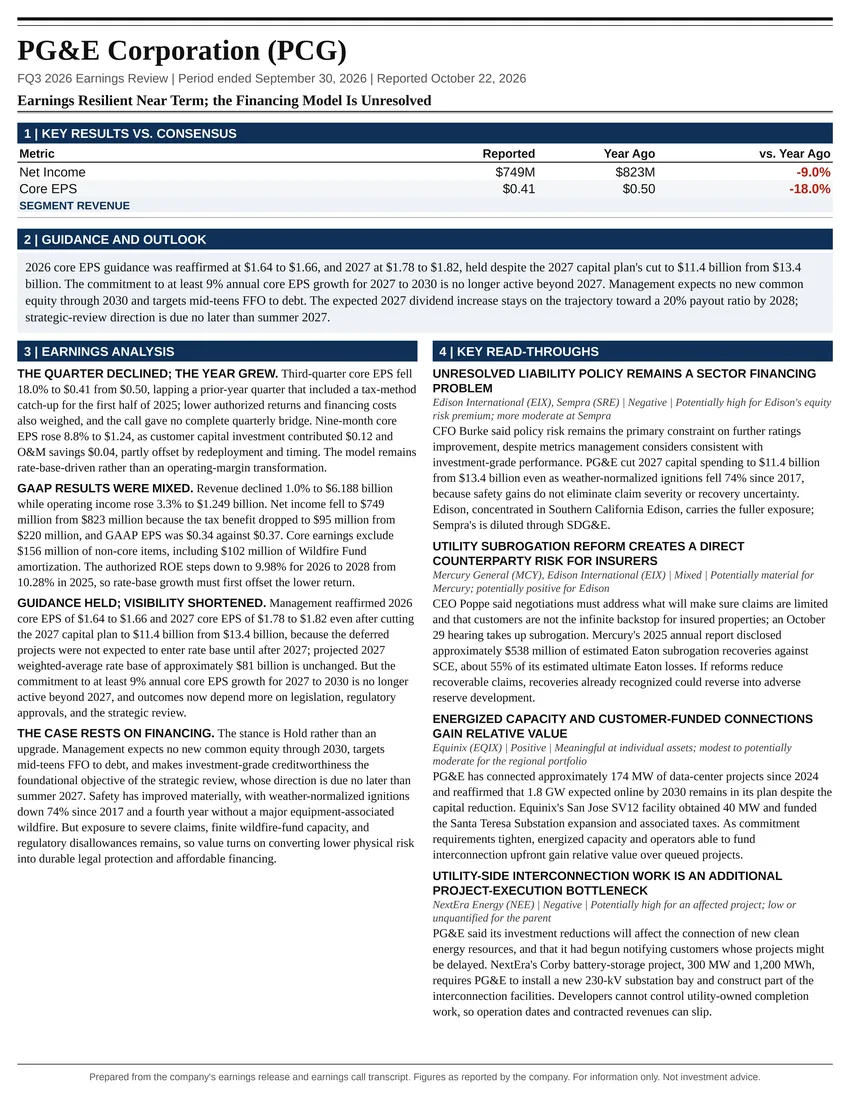
Earnings Resilient Near Term; the Financing Model Is Unresolved
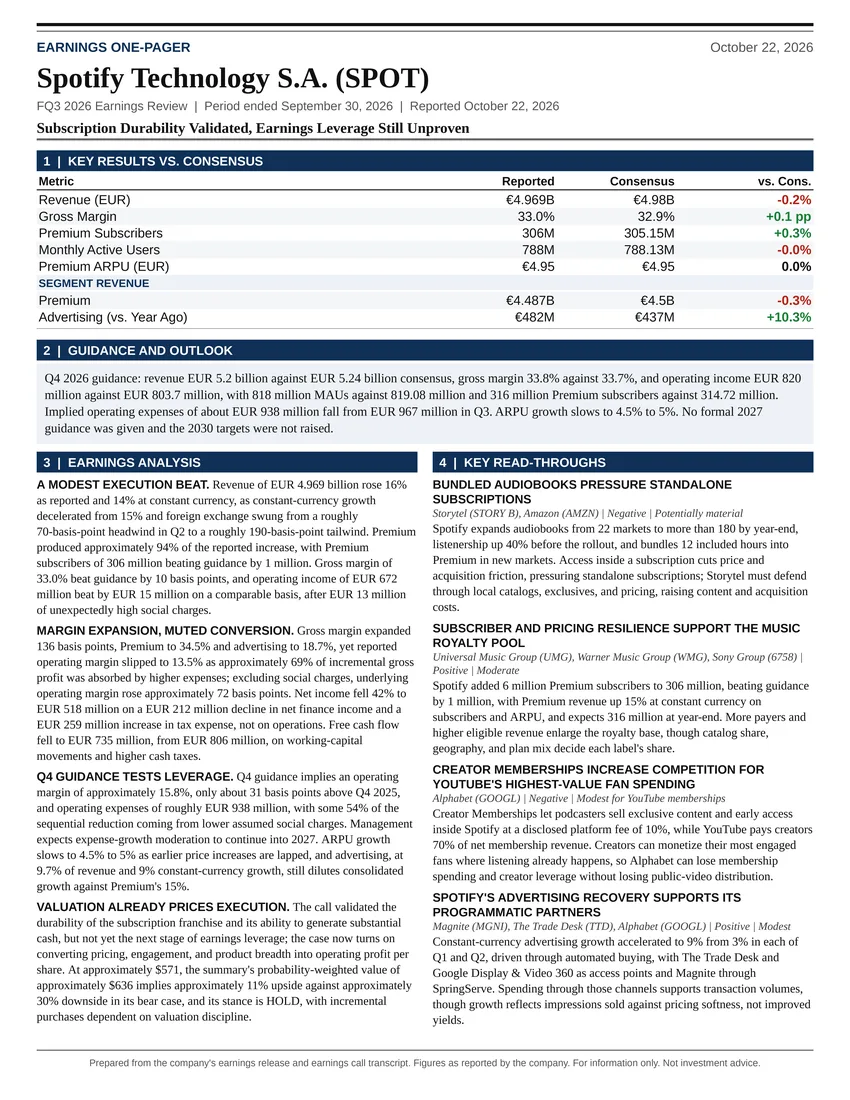
Subscription Durability Validated, Earnings Leverage Still Unproven
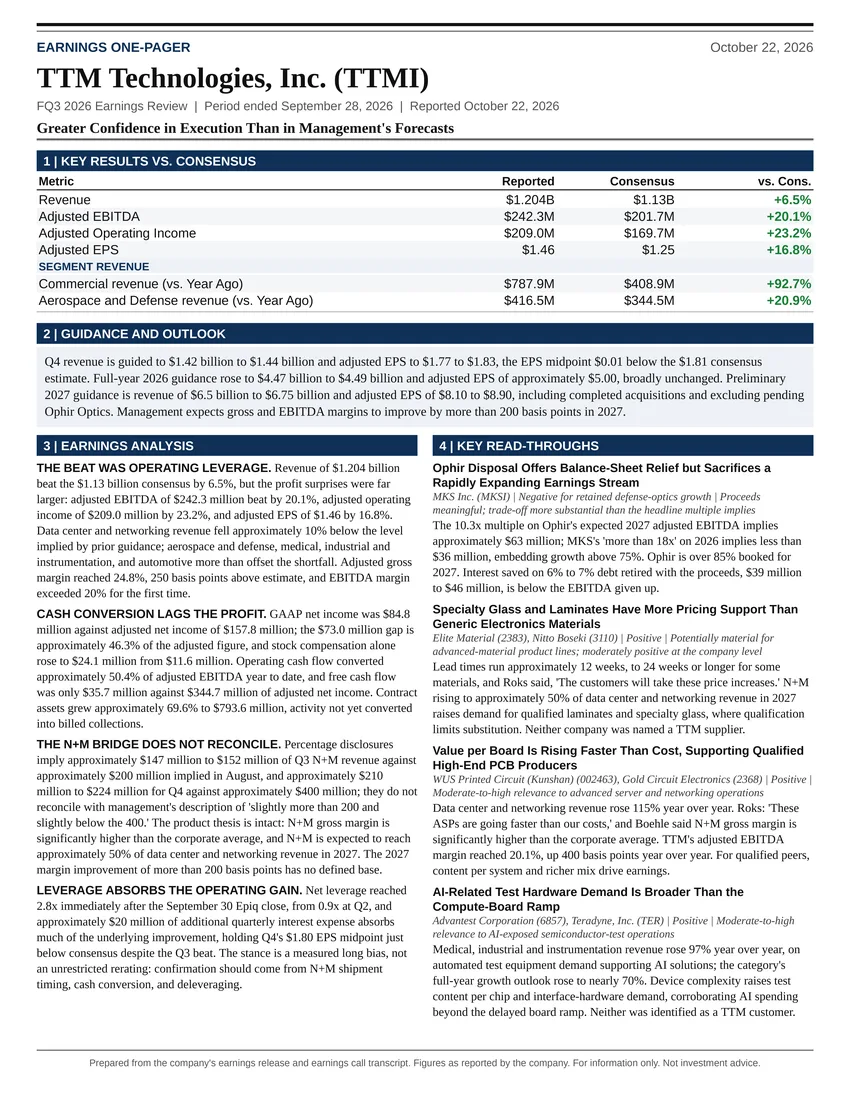
Greater Confidence in Execution Than in Management's Forecasts
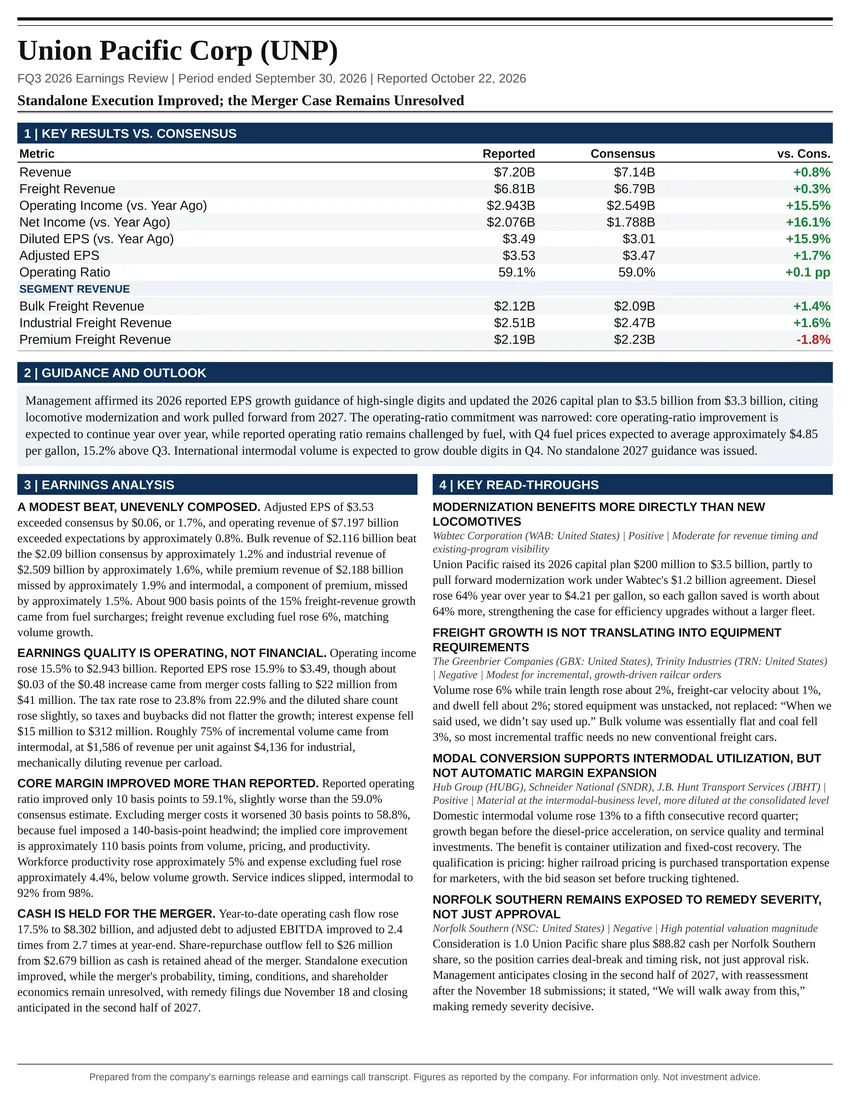
Standalone Execution Improved; the Merger Case Remains Unresolved
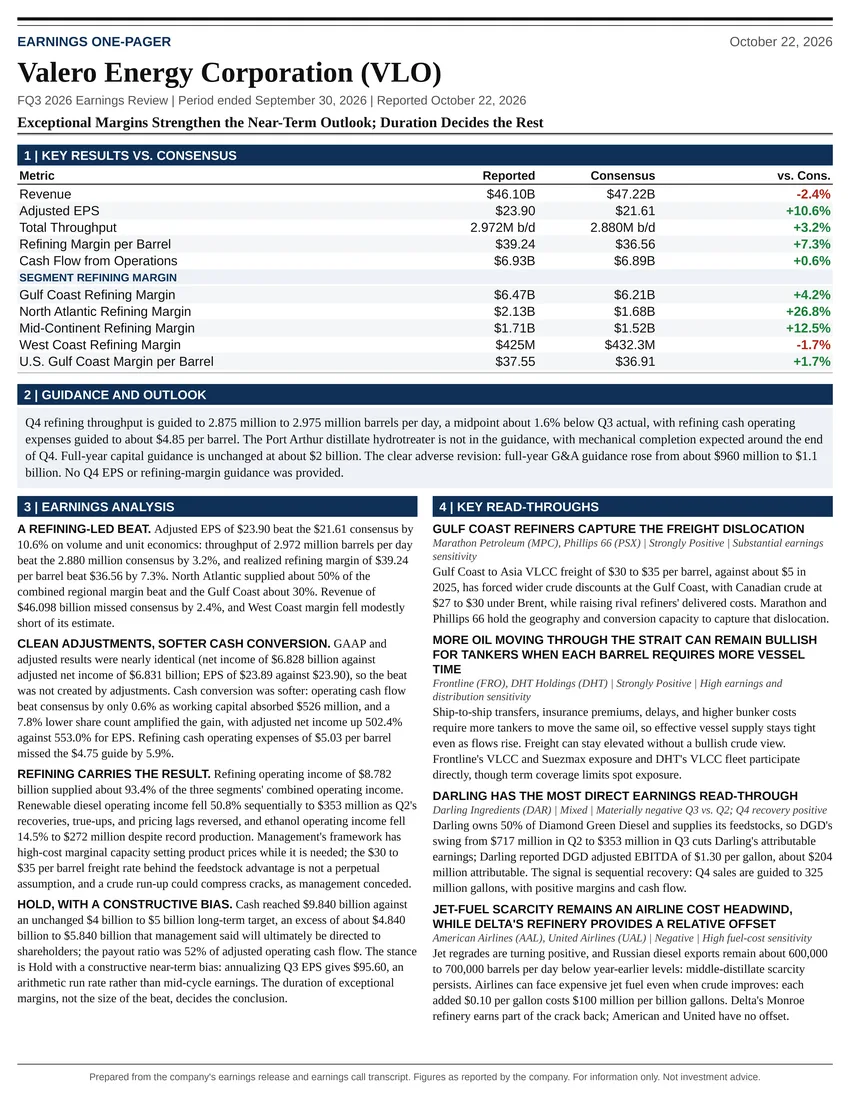
Exceptional Margins Strengthen the Near-Term Outlook; Duration Decides the Rest
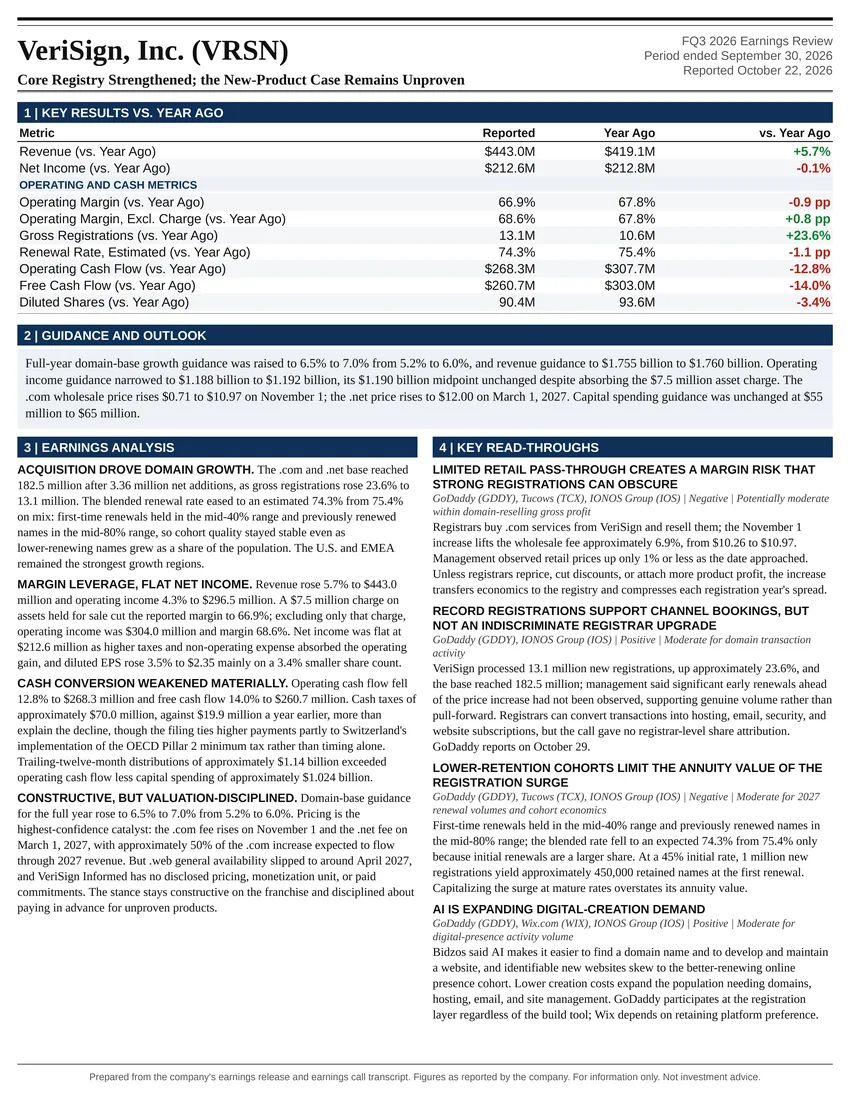
Core Registry Strengthened; the New-Product Case Remains Unproven
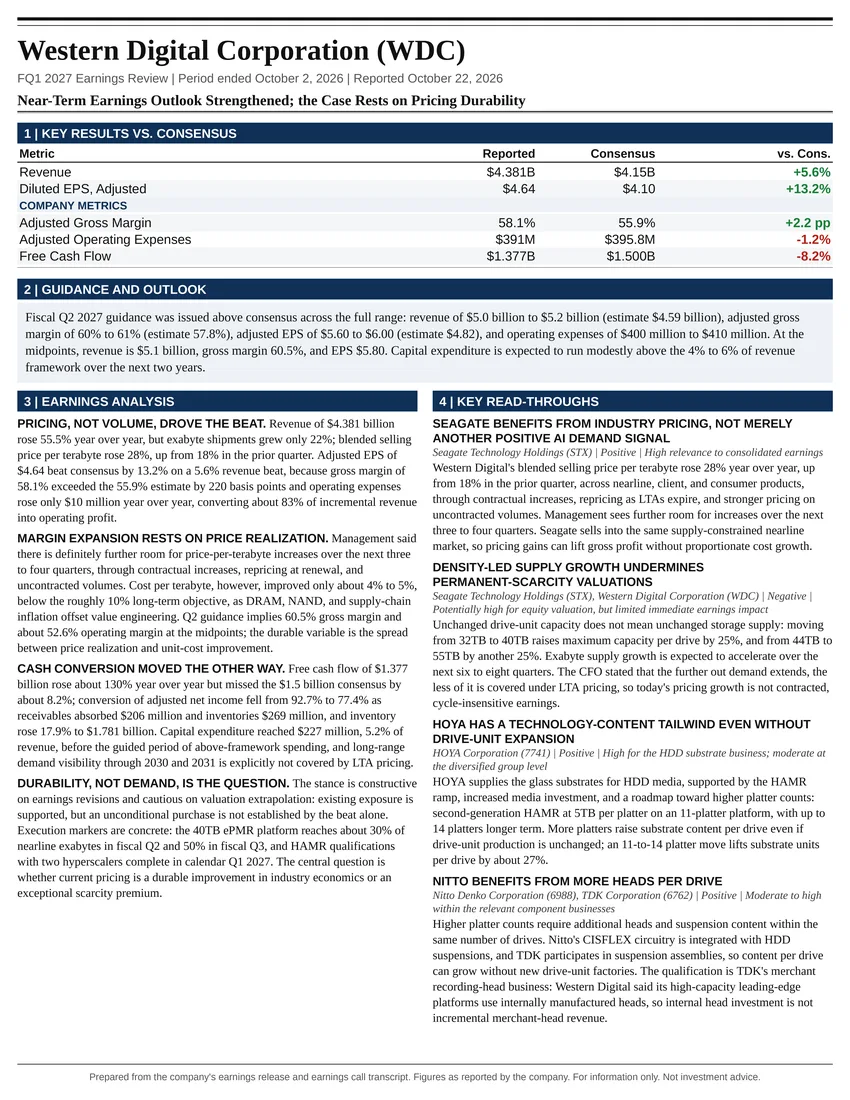
Near-Term Earnings Outlook Strengthened; the Case Rests on Pricing Durability
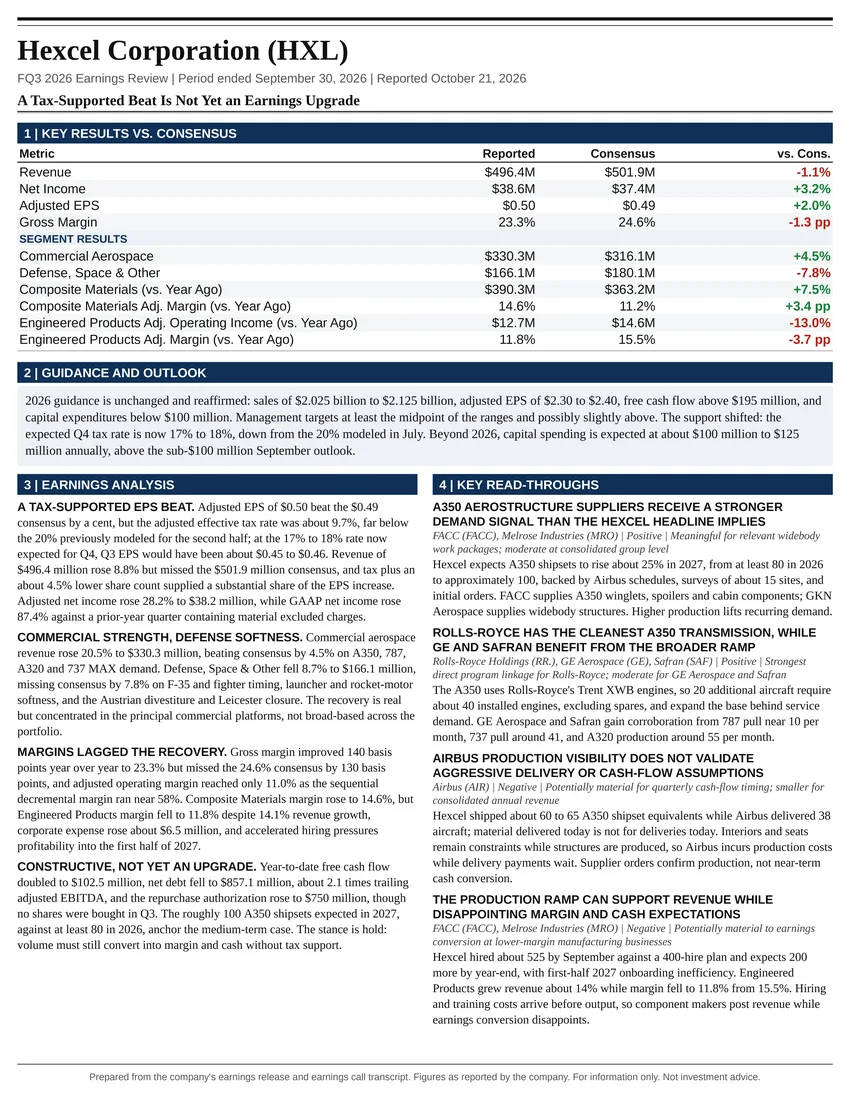
A Tax-Supported Beat Is Not Yet an Earnings Upgrade
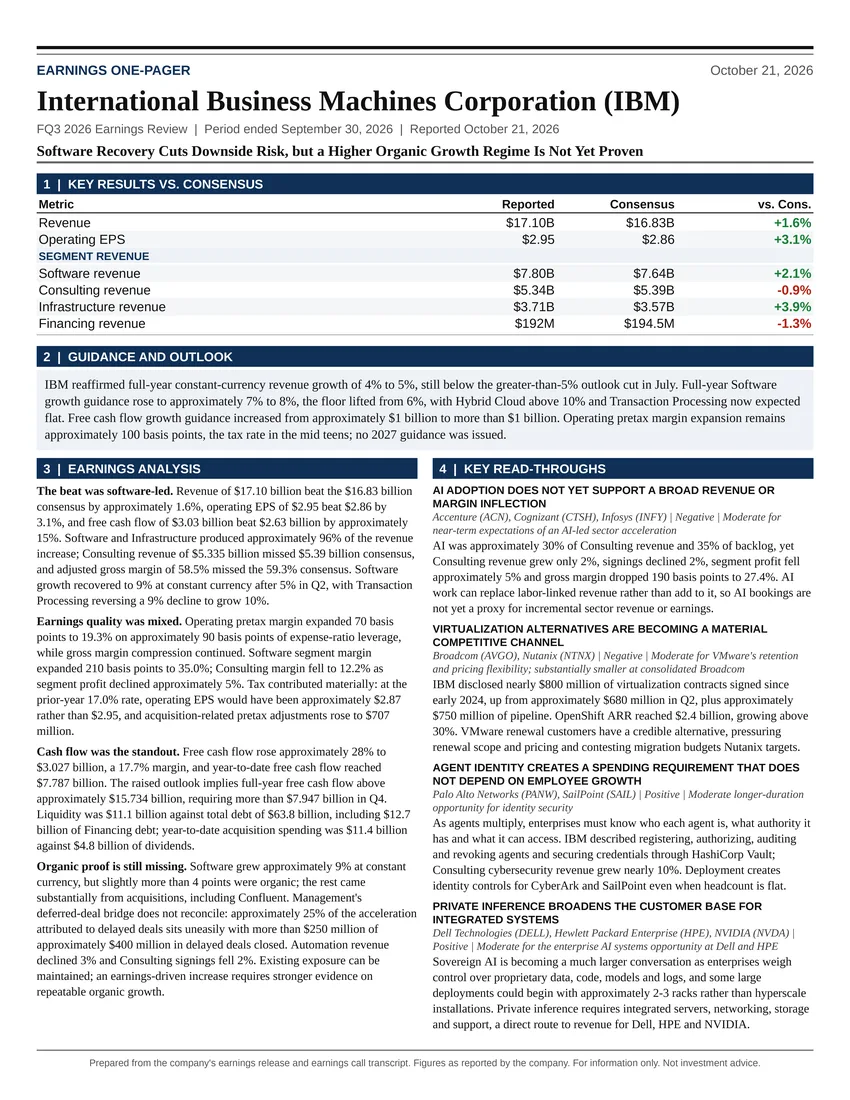
Software Recovery Cuts Downside Risk, but a Higher Organic Growth Regime Is Not Yet Proven
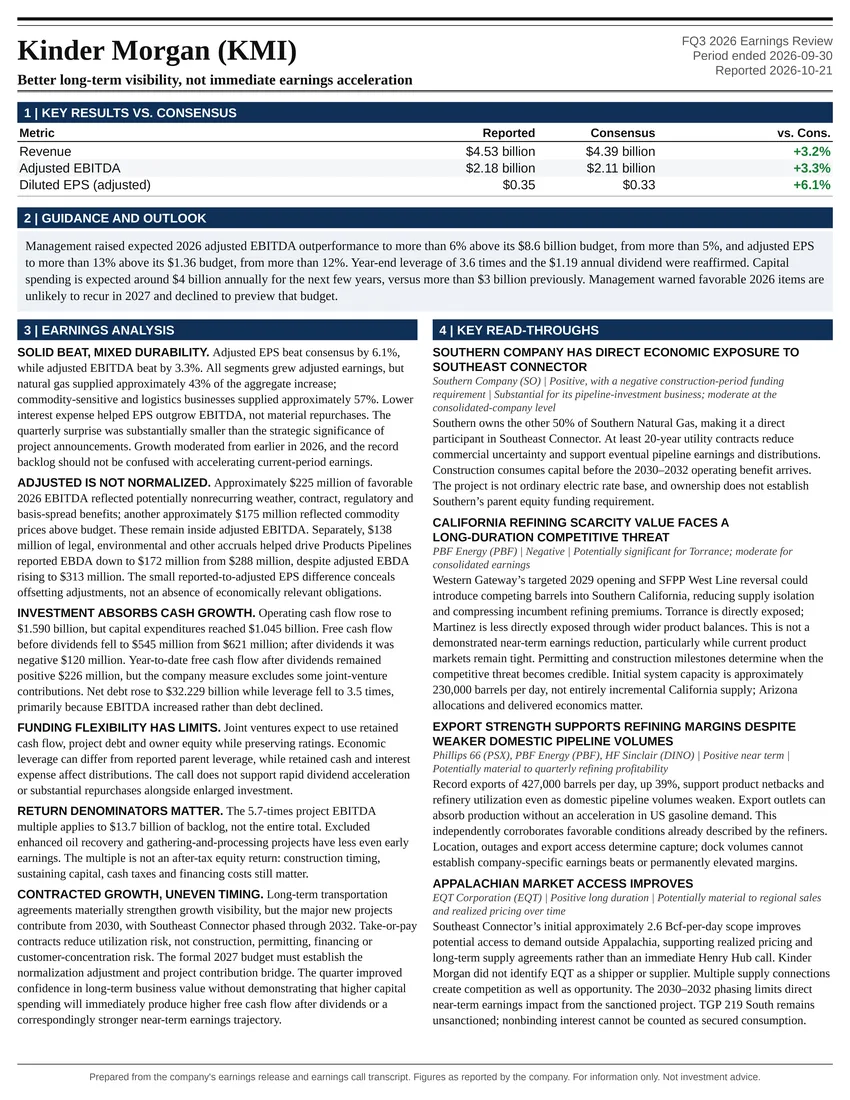
Better long-term visibility, not immediate earnings acceleration
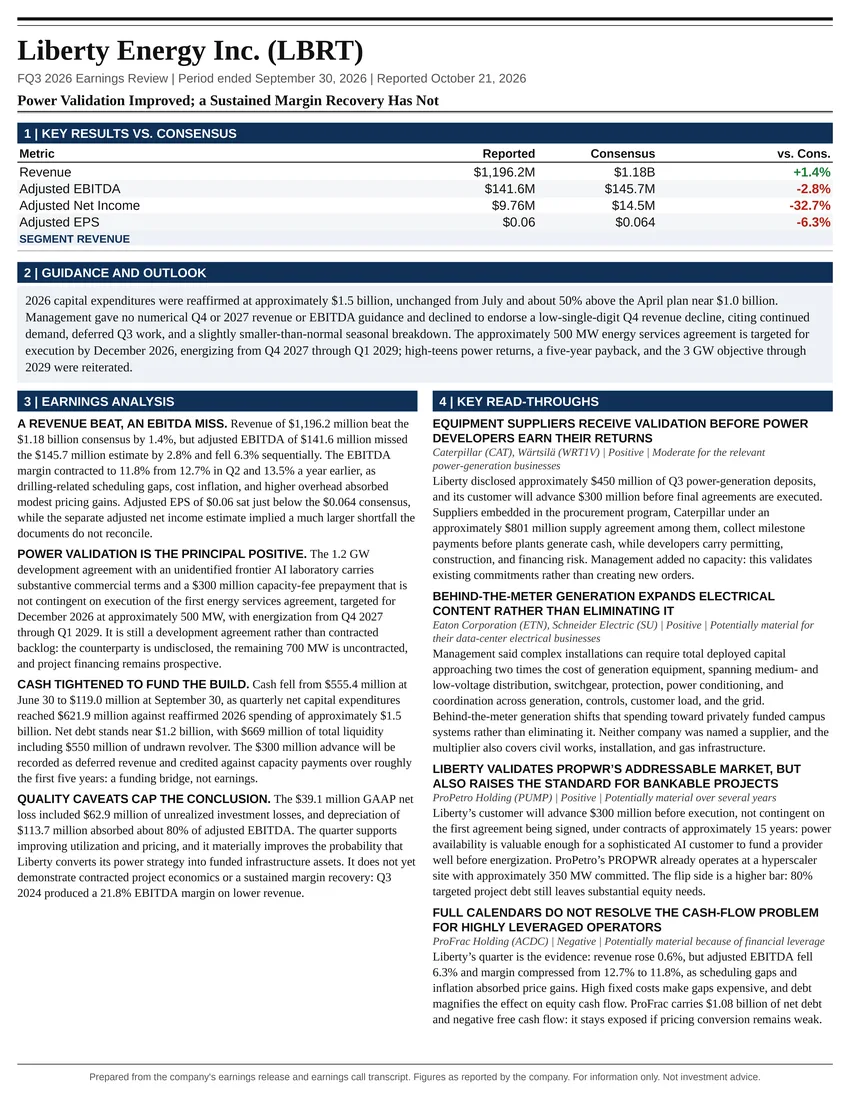
Power Validation Improved; a Sustained Margin Recovery Has Not
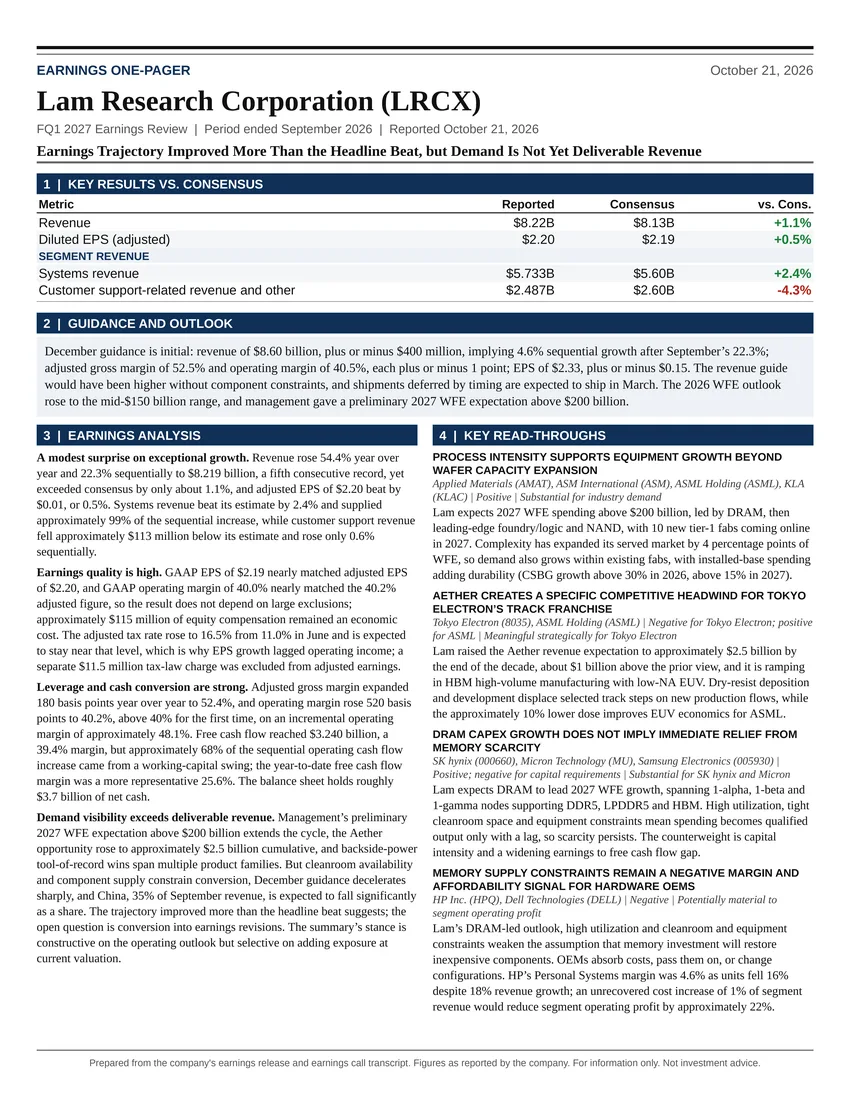
Earnings Trajectory Improved More Than the Headline Beat, but Demand Is Not Yet Deliverable Revenue
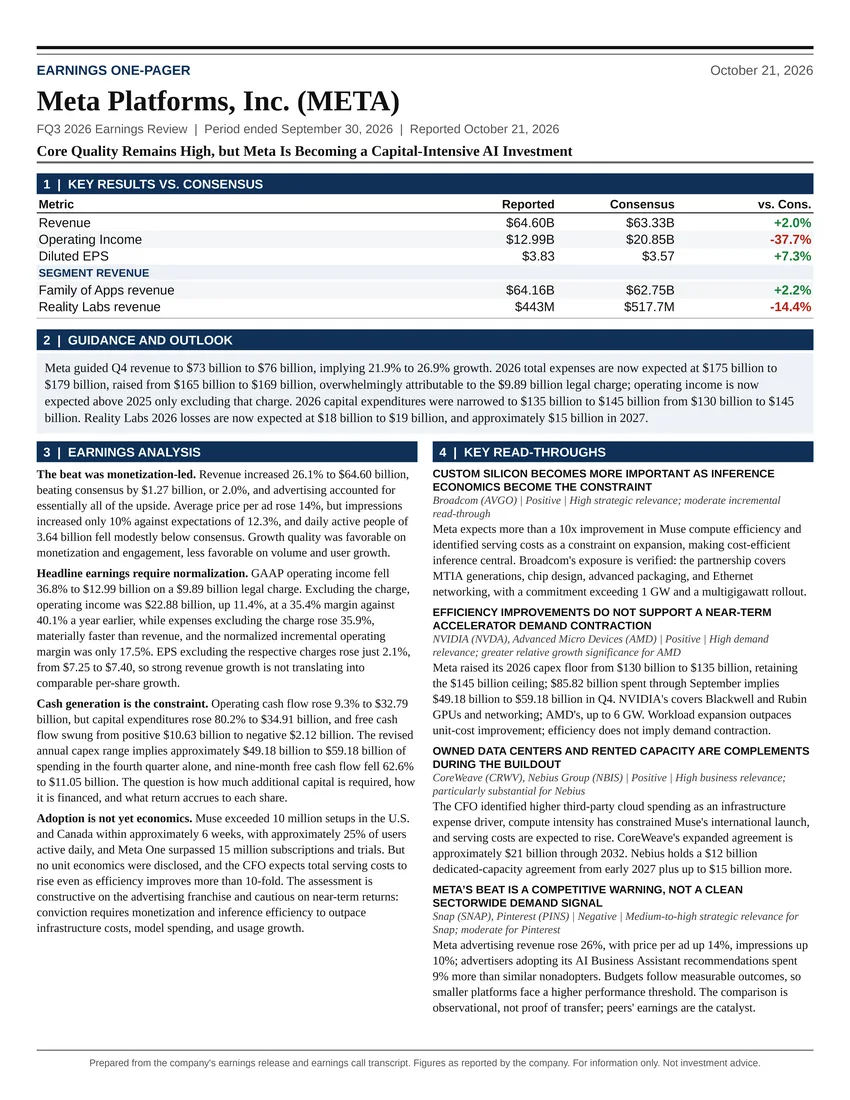
Core Quality Remains High, but Meta Is Becoming a Capital-Intensive AI Investment
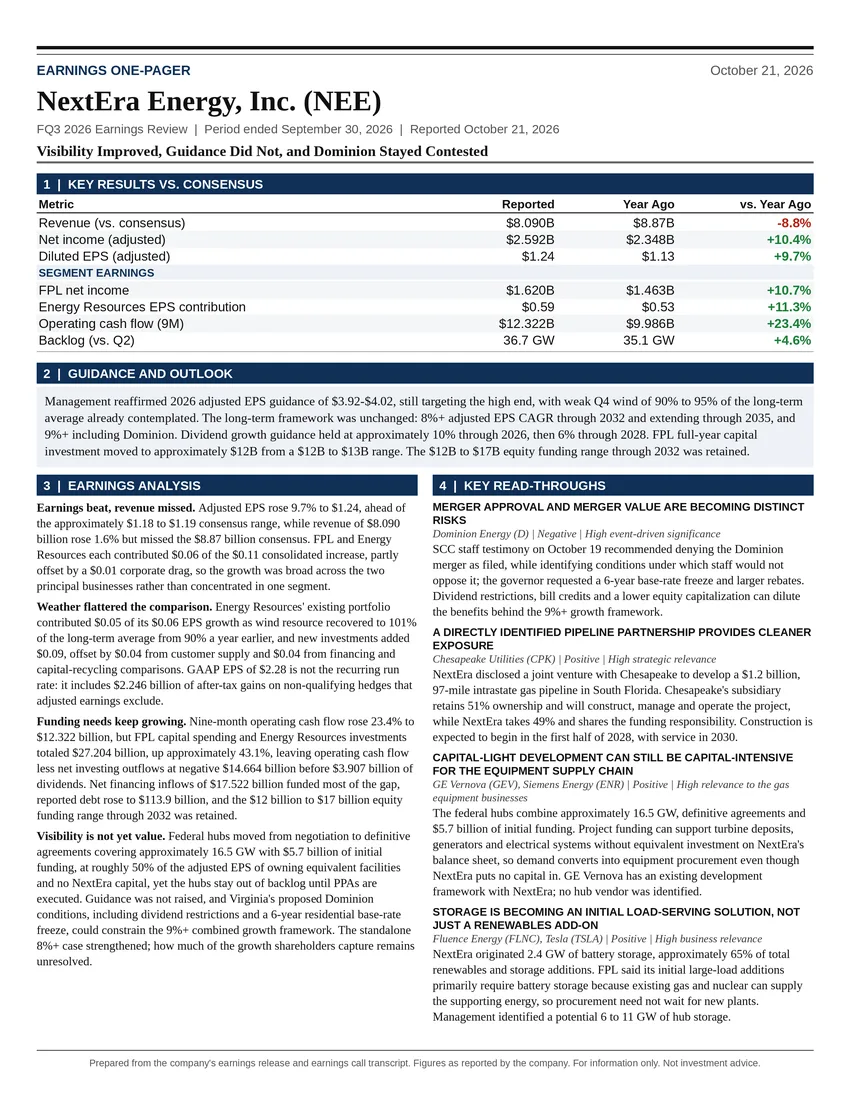
Visibility Improved, Guidance Did Not, and Dominion Stayed Contested
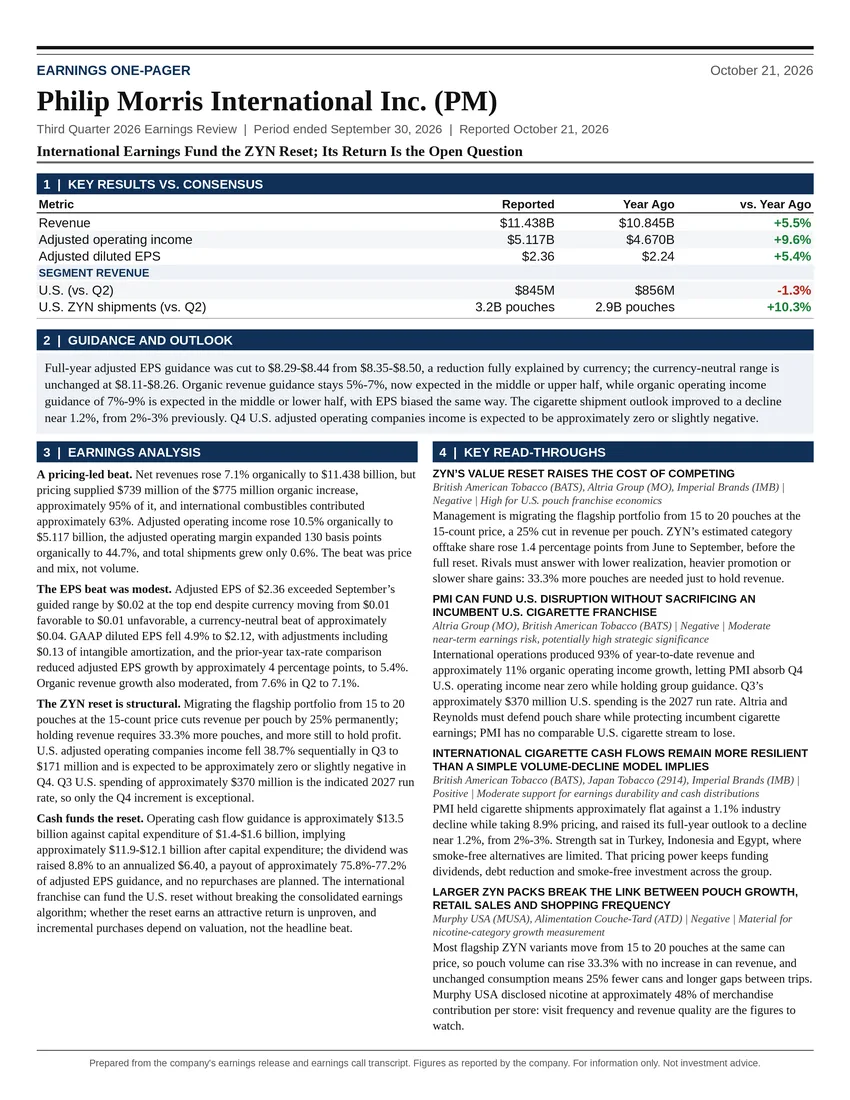
International Earnings Fund the ZYN Reset; Its Return Is the Open Question
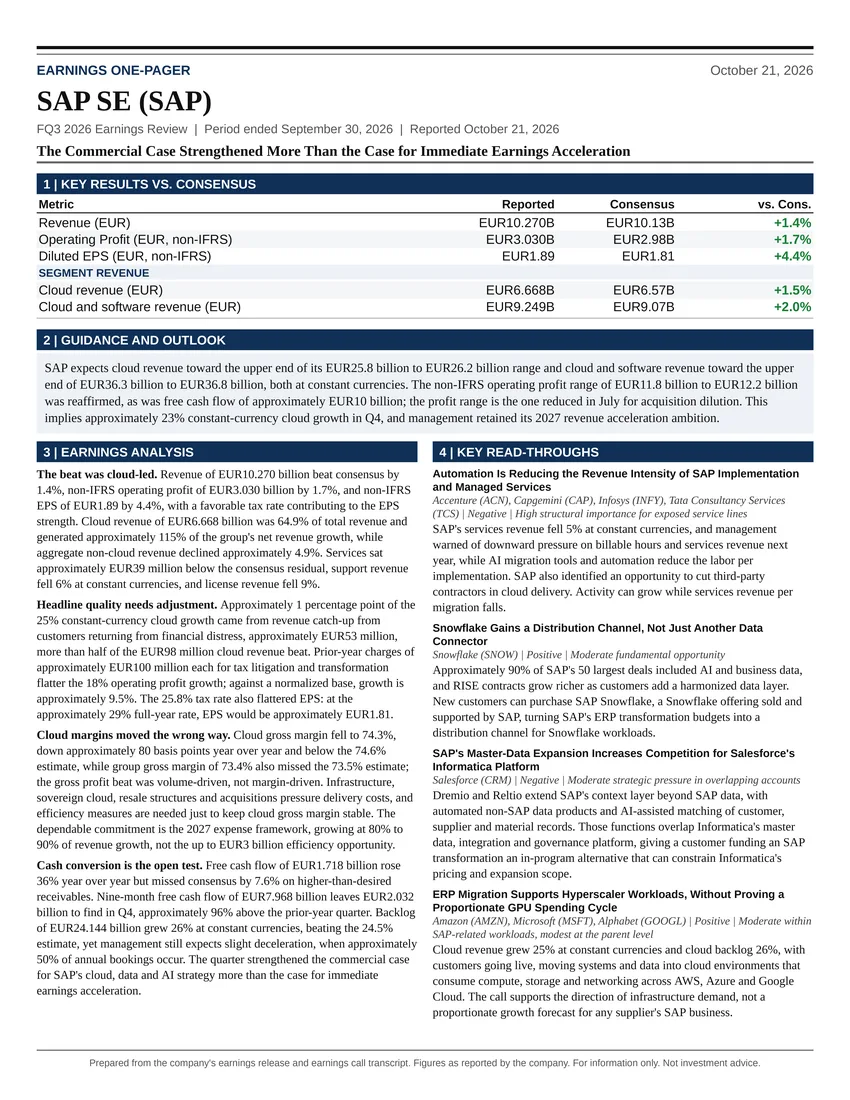
The Commercial Case Strengthened More Than the Case for Immediate Earnings Acceleration
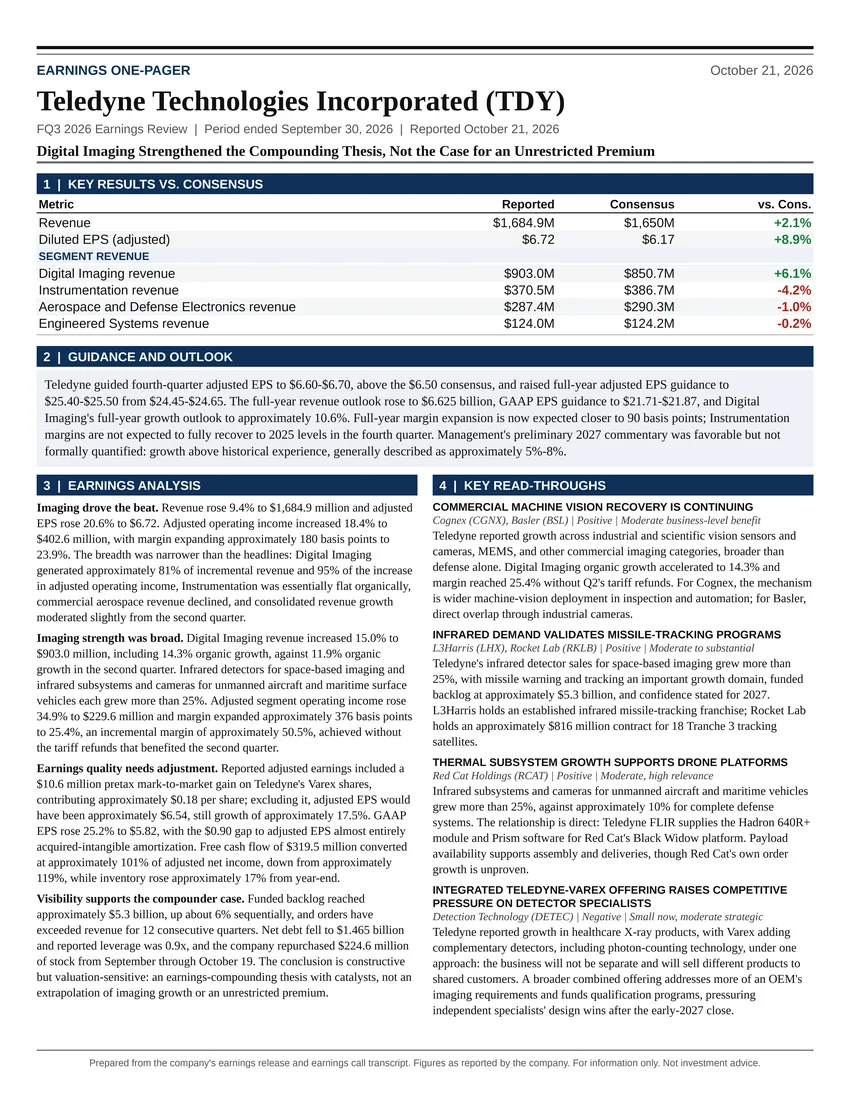
Digital Imaging Strengthened the Compounding Thesis, Not the Case for an Unrestricted Premium
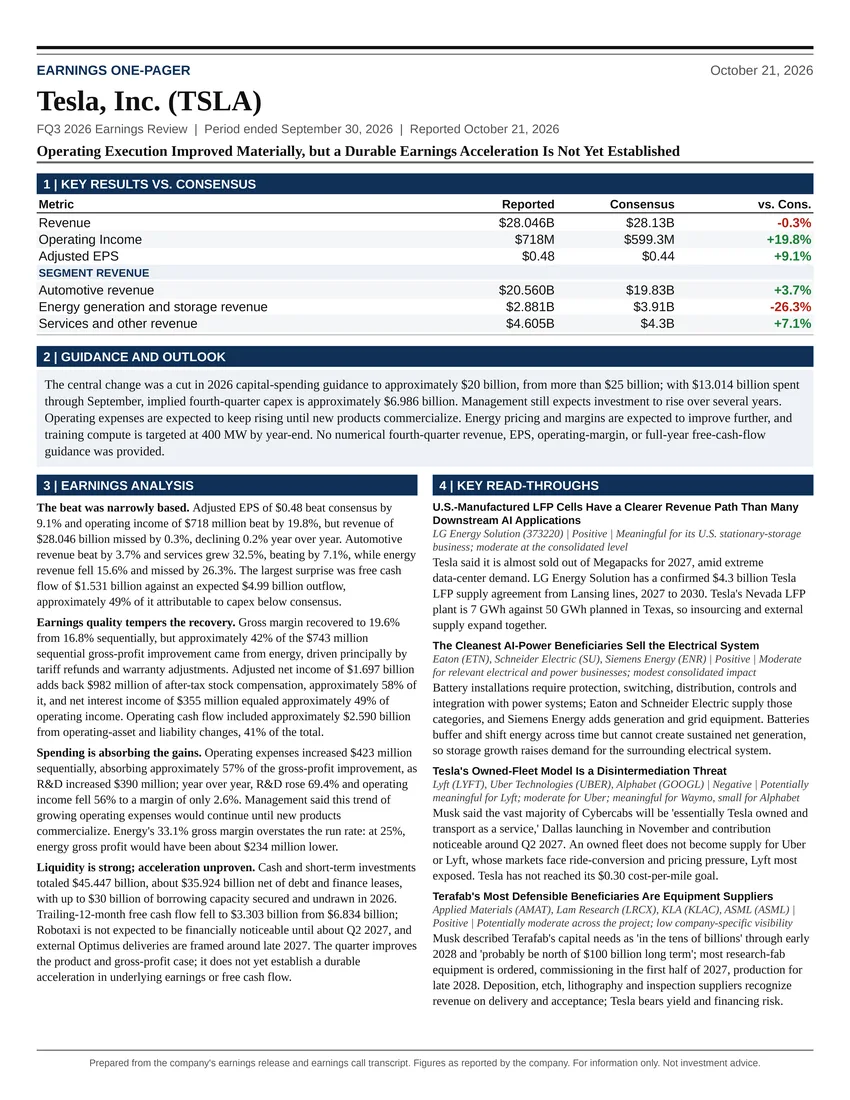
Operating Execution Improved Materially, but a Durable Earnings Acceleration Is Not Yet Established
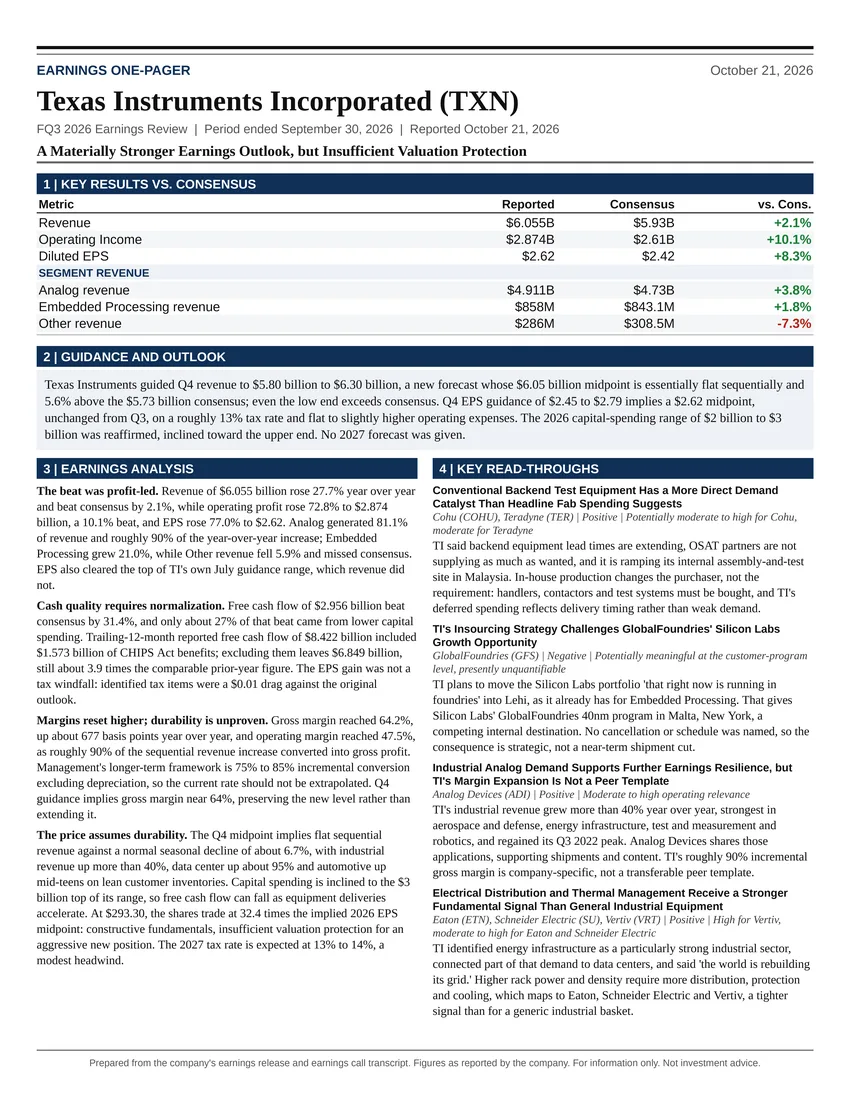
A Materially Stronger Earnings Outlook, but Insufficient Valuation Protection
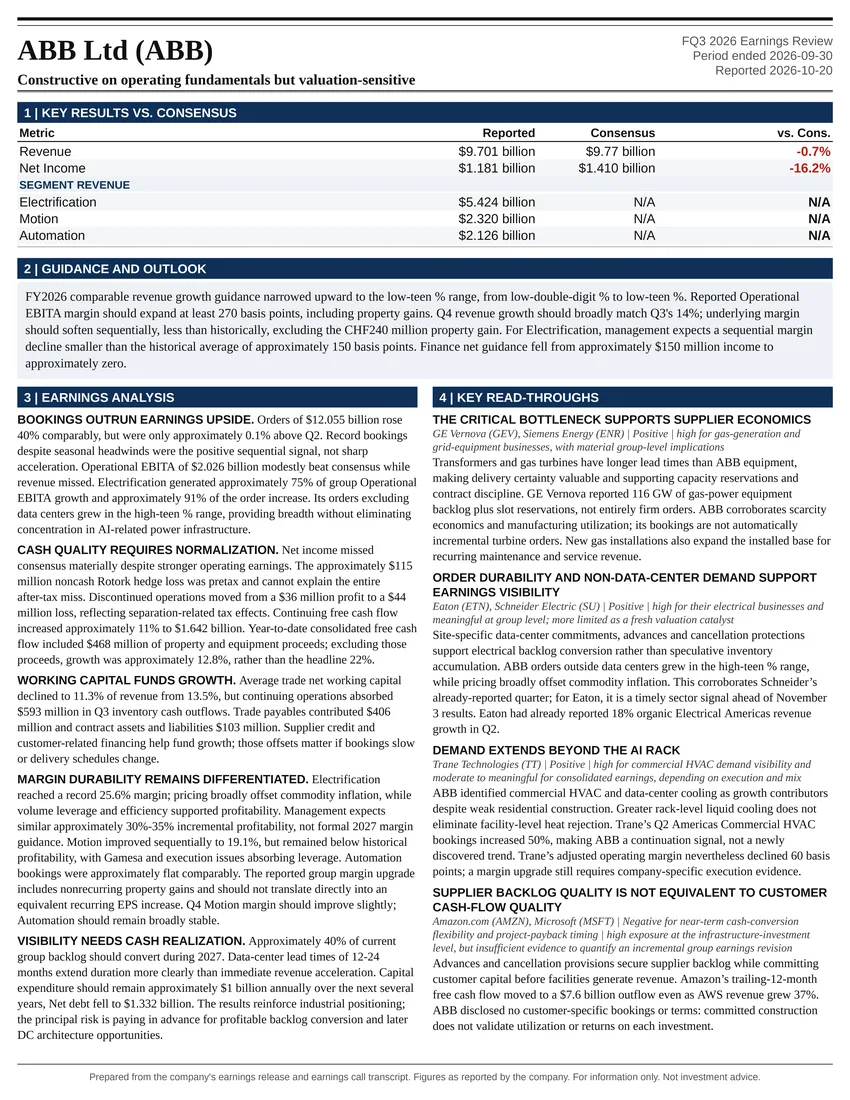
Constructive on operating fundamentals but valuation-sensitive
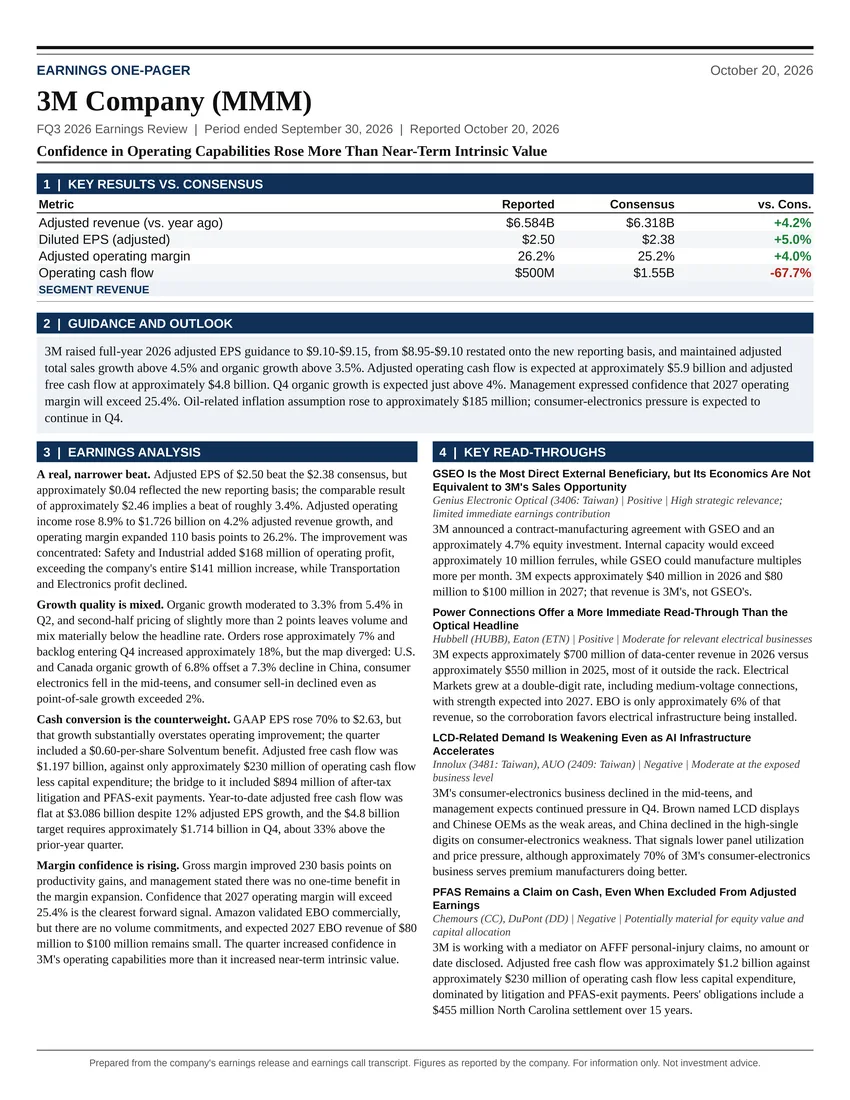
Confidence in Operating Capabilities Rose More Than Near-Term Intrinsic Value
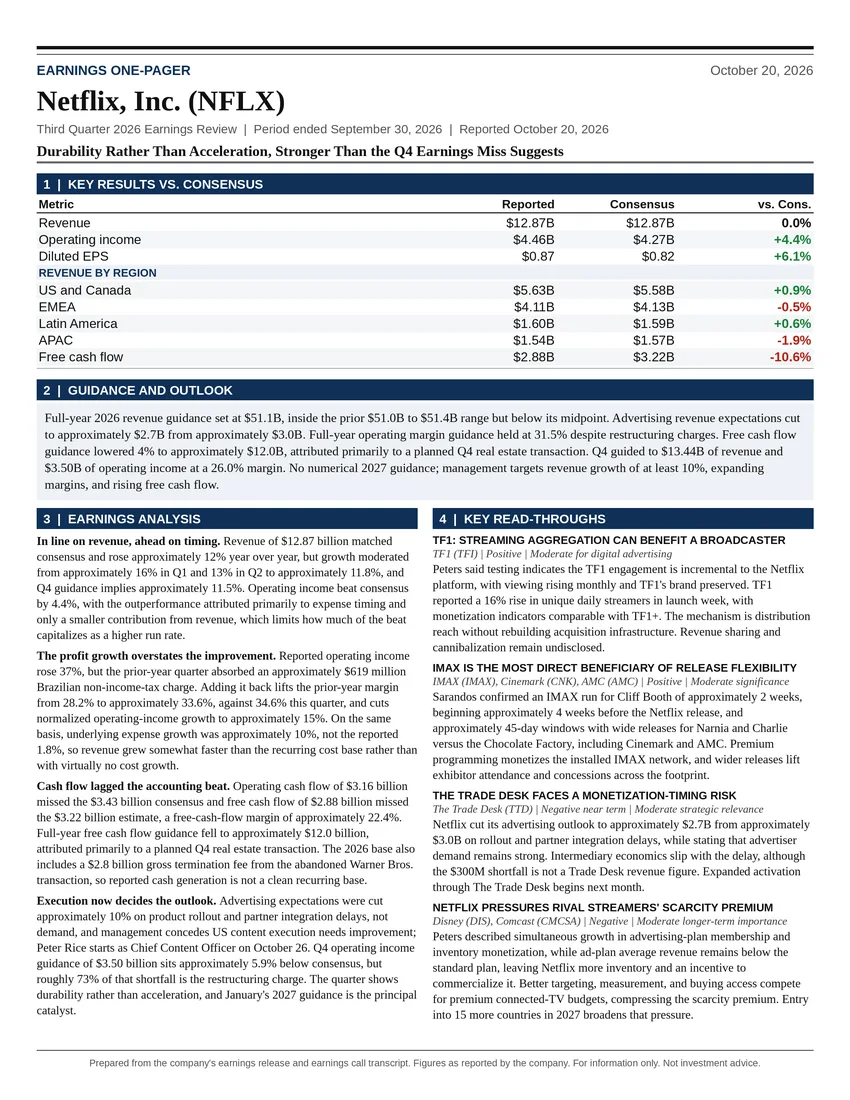
Durability Rather Than Acceleration, Stronger Than the Q4 Earnings Miss Suggests
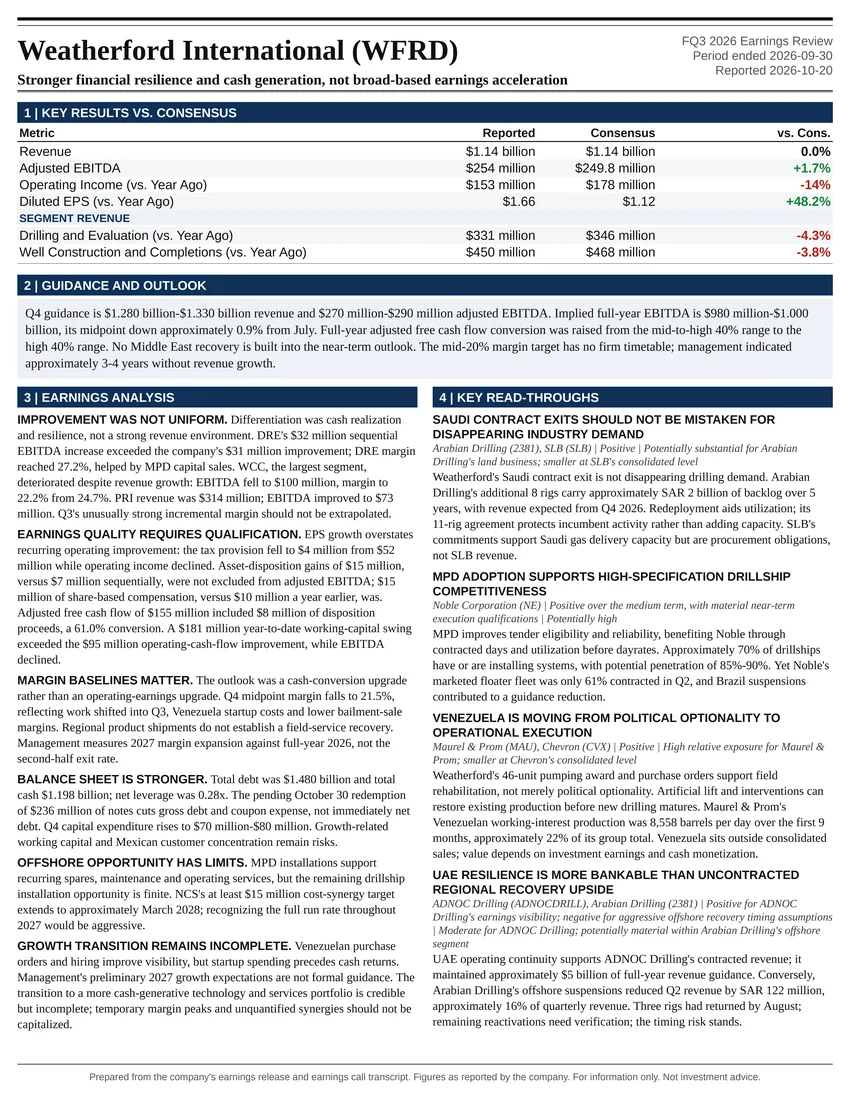
Stronger financial resilience and cash generation, not broad-based earnings acceleration
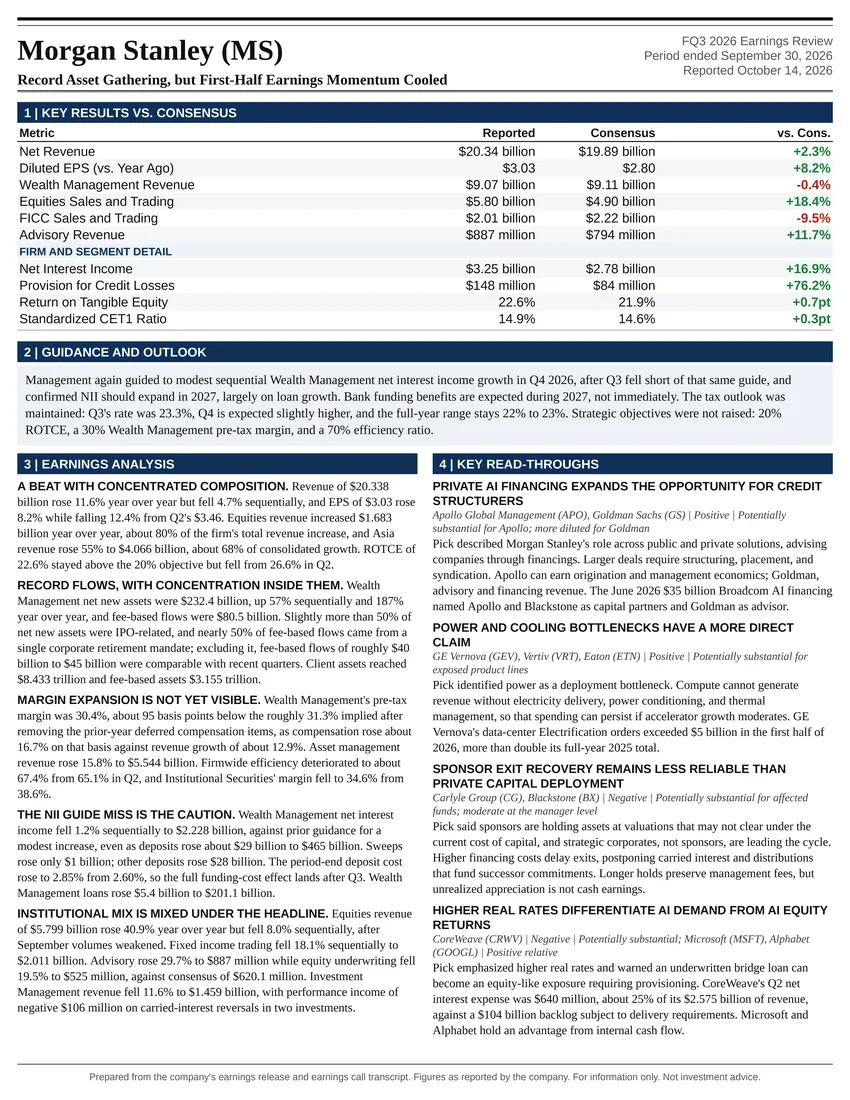
Record Asset Gathering, but First-Half Earnings Momentum Cooled
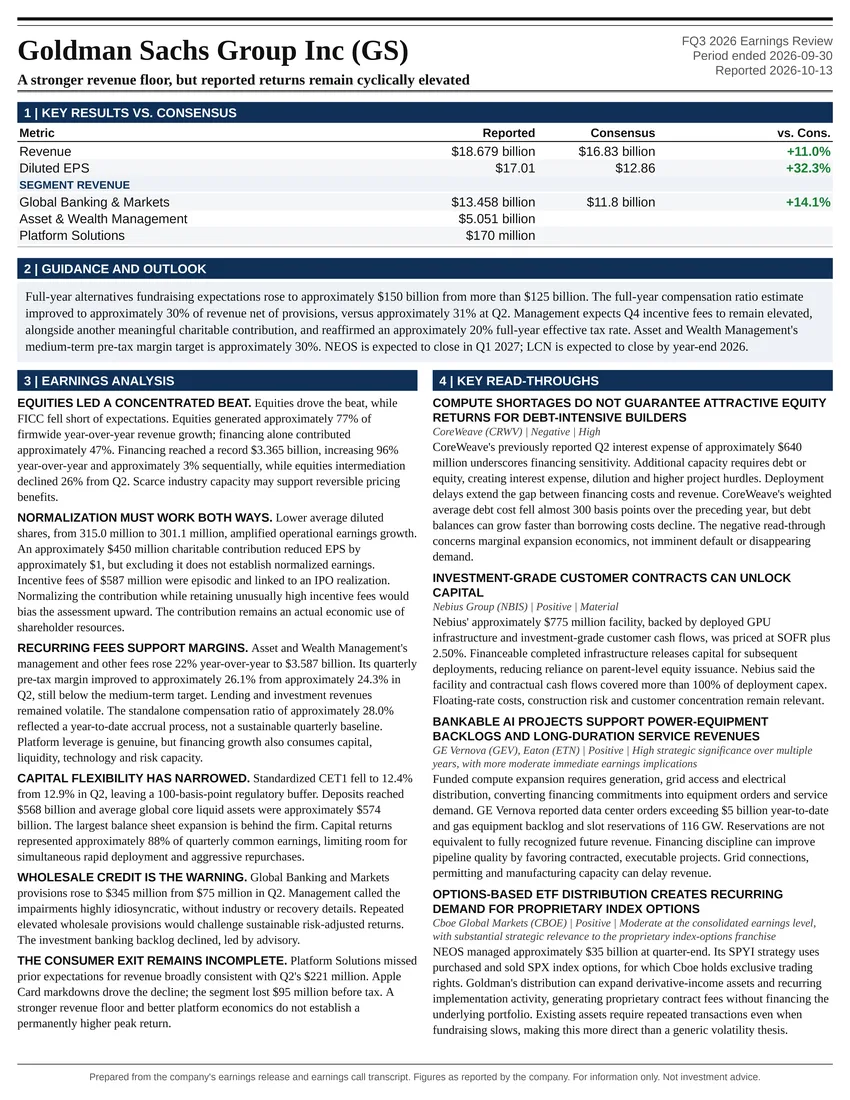
A stronger revenue floor, but reported returns remain cyclically elevated
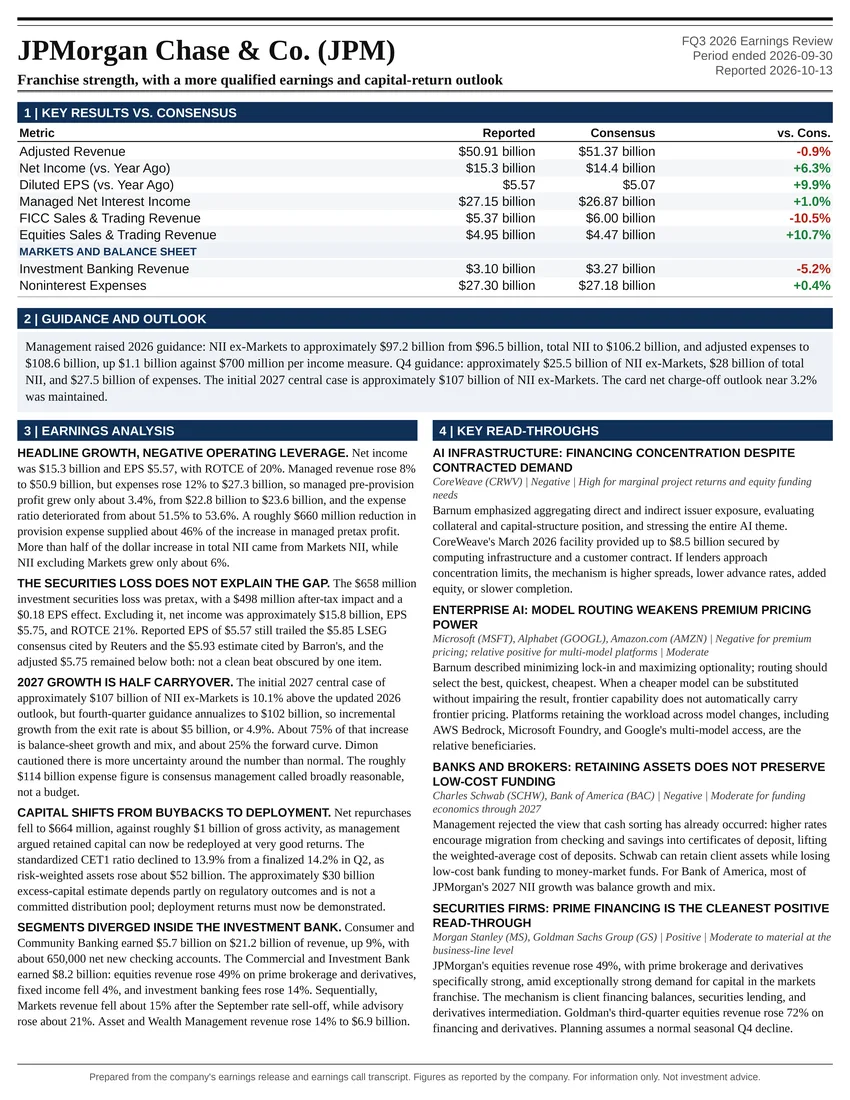
Franchise strength, with a more qualified earnings and capital-return outlook
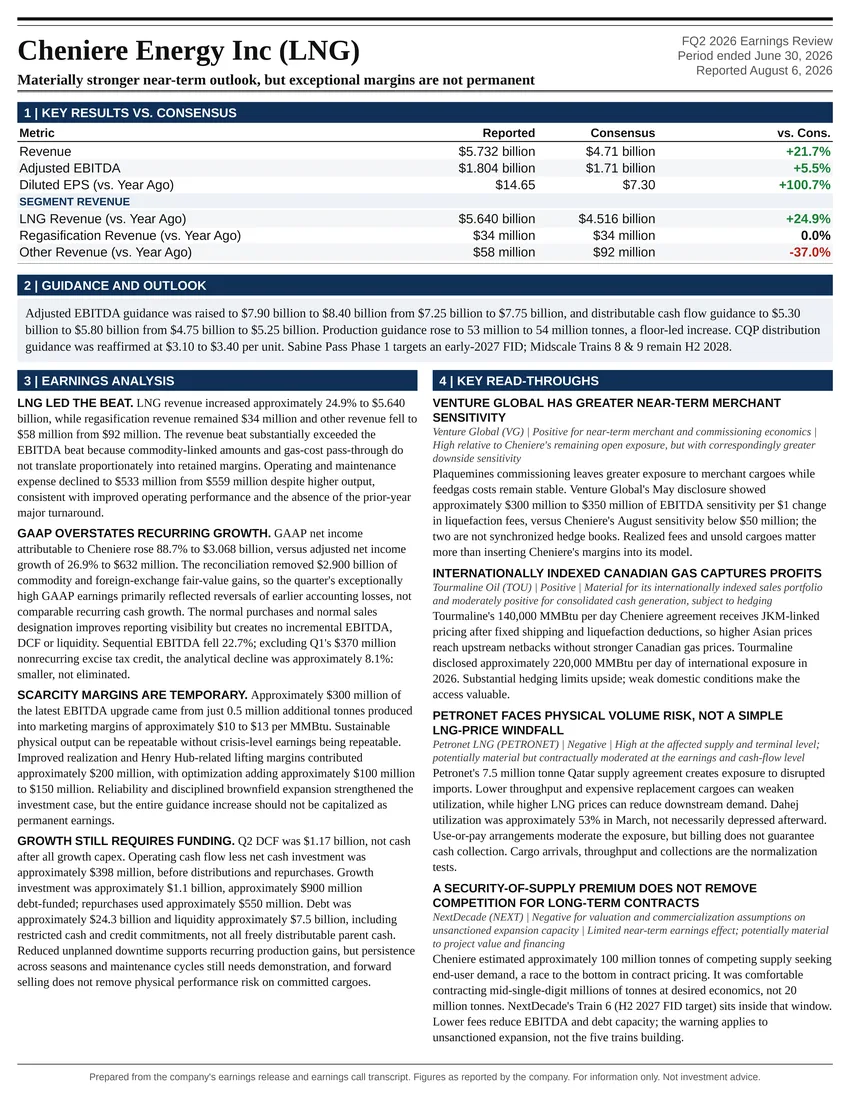
Materially stronger near-term outlook, but exceptional margins are not permanent
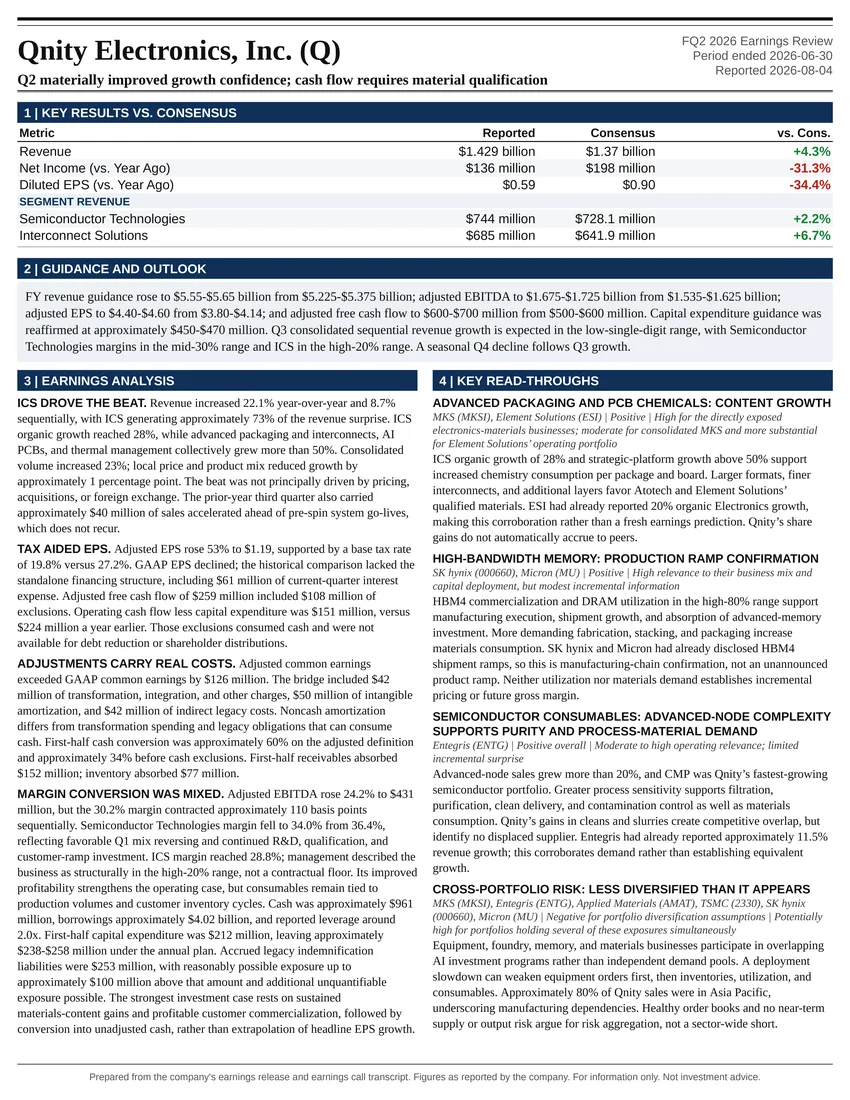
Q2 materially improved growth confidence; cash flow requires material qualification
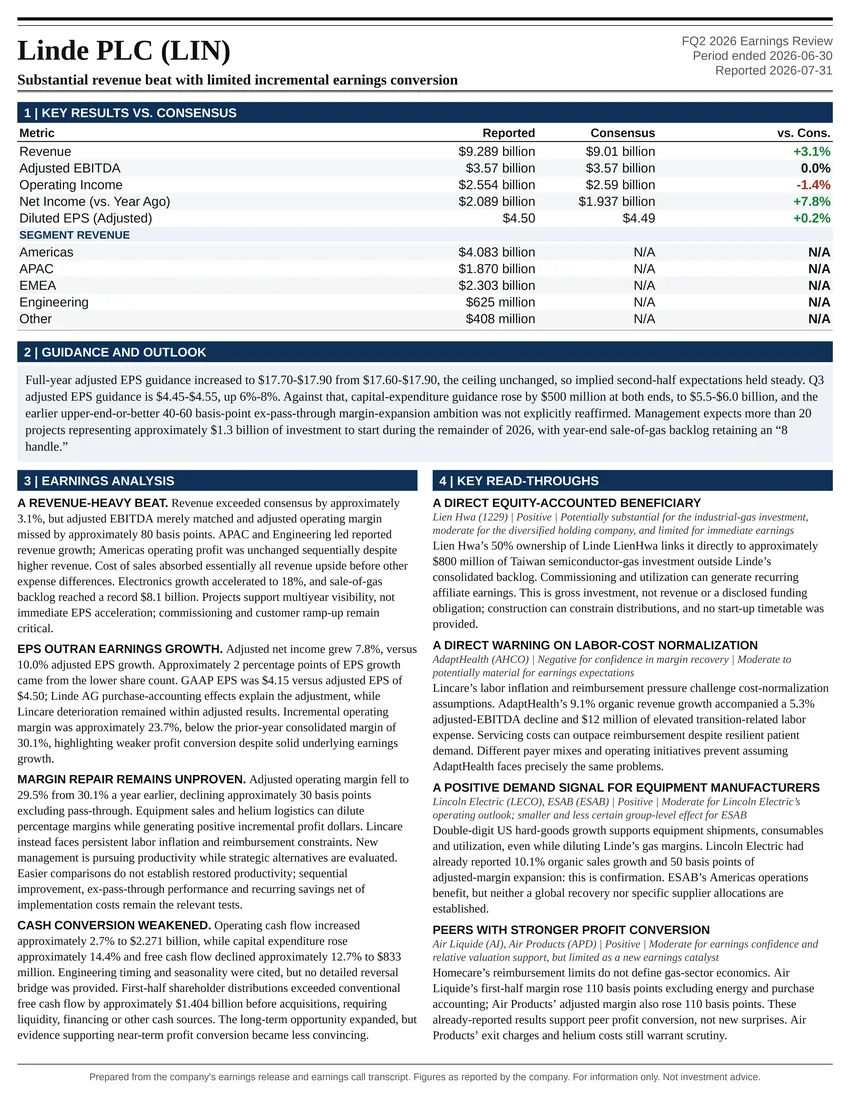
Substantial revenue beat with limited incremental earnings conversion
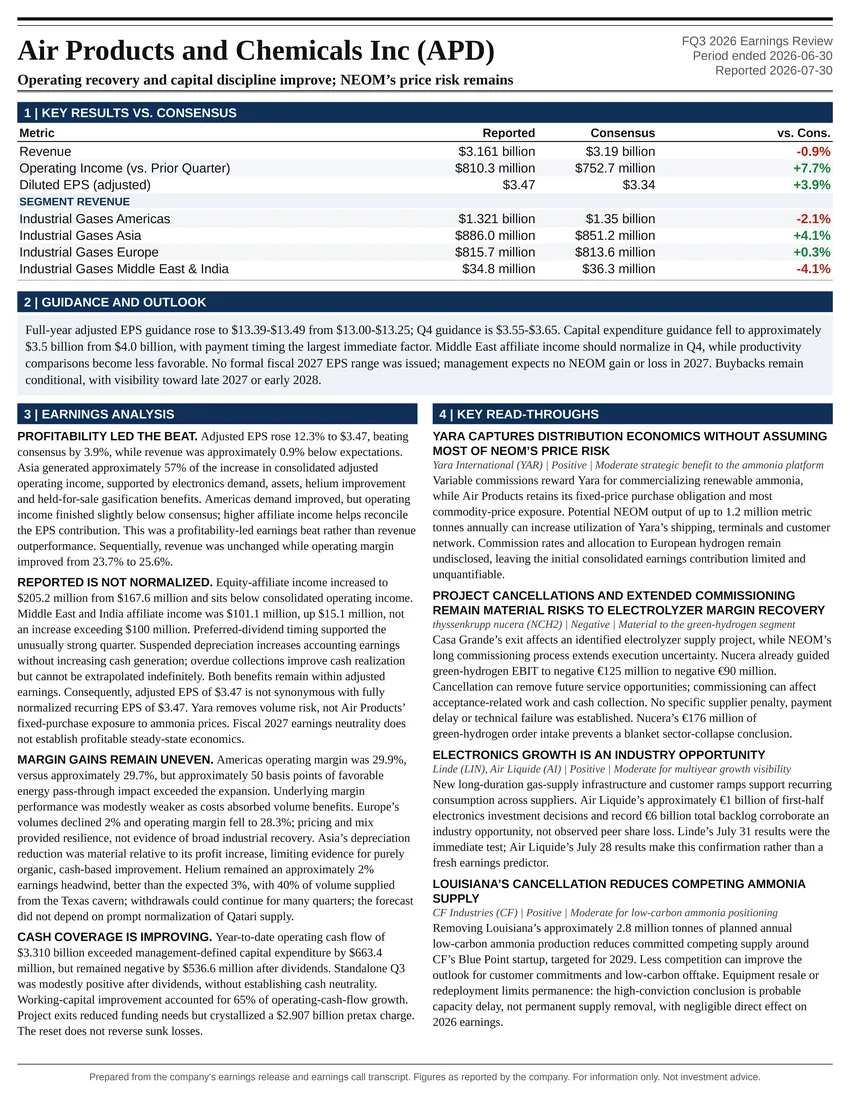
Operating recovery and capital discipline improve; NEOM’s price risk remains
About these reports
- What a report is: Atlas Peak Research's full earnings coverage of one company for one fiscal period, published as reported.
- Four components: every report carries the complete earnings analysis document, the complete read-through document, the one-page exhibit, and the one-page report as a PDF download.
- Sources: figures are as reported by the company in its earnings release and on its earnings call.
- Corrections: a corrected report is republished at the same address with the change recorded on the site changelog.
Prepared from the company's earnings release and earnings call transcript. Figures as reported by the company. For information only. Not investment advice.